
KBank helps fulfil central bank's hopes


Play
Kasikornbank takes the lead in cutting lending rates, being the first to do so since the Bank of Thailand slashed the policy rate by 25 basis points on April 29.
After the policy rate cut in March to 1.75 per cent, only five banks acted in slashing their rates.
Before KBank, no bank took any action after the policy rate cut to 1.5 per cent in April.
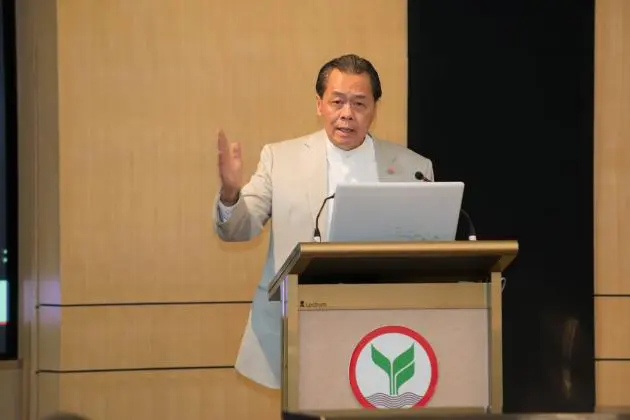
"I urged other banks to cut rates, to help shore up the economy," said KBank Chief Executive Officer Banthoon Lamsam at the press conference today.
Effective tomorrow, the minimum overdraft rate (MOR) and minimum loan rate (MLR) will be cut by 13 basis points. The bigger cut in MRR is meant specifically to help small and medium-sized enterprises (SMEs).
Poor external demand is dampening the Thai economy, as the export sector contributes some 70 per cent to the gross domestic product. Hopes are on government spending to boost the economy this year, which is widely expected to grow less than 4 per cent. This is despite the low growth base of 0.7 per cent in 2014.
The Bank of Thailand's actions in March and April were a surprise. Though rate cuts are supported by easing inflation, economists did not expect the actions.
Across the Asia Pacific, inflation is expected to decelerate to 3.3 per cent in 2015, from 3.9 per cent in 2014, according to the UNEscap's Economic and Social Survey of Asia and the Pacific" report. This results from a combination of somewhat reduced economic activity and lower international oil prices.
Thailand’s export growth was flat in 2013 and 2014, in contrast with the strong performance of Malaysia and Vietnam and with its annual average growth of 13 per cent in the preceding decade. Some argue that Thailand’s electrical and electronics sector, which relies heavily on manufacturing hard disk drives, failed to adjust to modern technologies and trends.
2014 marked the second consecutive year of negative export growth for Thailand, which contrasts with the annual average pace of growth of about 13 per cent in the period 2002-2012.
Economic growth in Southeast Asia as a whole moderated to 4.3% in 2014 from 5% in 2013. Thailand was the clear underperformer owing to political unrest, but growth also slowed in Indonesia to the weakest level in five years as a result of monetary tightening and weak commodity exports. Malaysia, the Philippines and Viet Nam posted robust growth rates of 6% or more on the back of strong investment and export performance. Growth eased, albeit from a high base, in Cambodia, the Laos and Myanmar, slowing the pace of their income convergence with the more developed economies in the subregion.
Escap forecasts 3.9-4 per cent economic growth rate for Thailand in 2015 and 2016. This is below the Asean average of 4.9 per cent in 2015 and 5.1 per cent in 2016.
