
SCG hopeful of economic revival in H2


Play
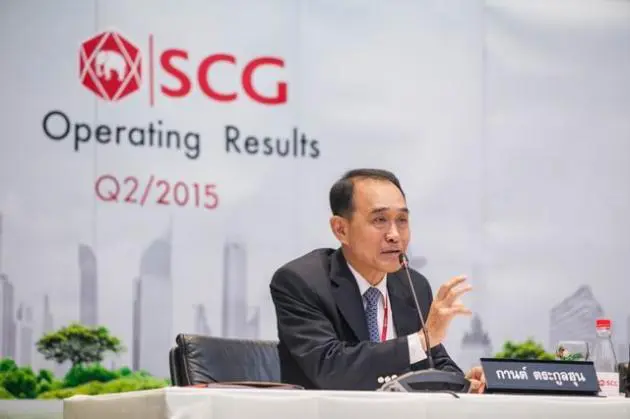
SIAM CEMENT Group is confident the economy will recover in the current second half of the year thanks to government spending on infrastructure, which will boost the demand for cement. Already in the second quarter, demand for cement grew by 2 per cent,
He forecast that demand for cement would increase by 6 per cent in the second half, resulting in full-year growth of 3 per cent. This would be a recovery from the slump that began last year.
Meanwhile, SCG has maintained its 2015 revenue-growth target at 1-2 per cent even though income during the first half fell 10 per cent year on year to Bt223.09 billion. Net profit was Bt24.95 billion in the first half, up 48 per cent, thanks to the wide spread in its chemicals business between raw-material costs and finished products.
Last year, SCG posted revenue of Bt487.54 billion and net profit of Bt33.61 billion.
“In the second quarter of this year, we showed revenue of Bt113.81 billion and net profit of Bt13.87 billion, up 4 per cent and 25 per cent from the first quarter, thanks to the wide spread in the chemicals business and the demand for cement recovering both domestically and in Asean countries,” Kan said.
Based on the high net profit in the first half, the company’s board of directors approved an interim dividend of Bt7.50 per share, totalling Bt9 billion, for shareholders recognised on August 13. The dividend will be paid on August 27.
The company’s investment plan for this year has a budget worth between Bt50 billion and Bt60 billion. Of that, Bt24.3 billion was invested in the first half. Up to 60 per cent of its total investment budget will go into Asean countries.
The investment programme will be funded from cash flow and the issue of a debenture worth Bt30 billion in the first quarter of this year, he said.
In the first half, 23 per cent of its total revenue, or Bt49.84 billion, came from its business in Asean countries. SCG targets 25 per cent of its total revenue in the first half of 2016 coming from its Asean interests. Its cement plants in Indonesia, Myanmar and Laos will start operations between this year and 2017, he said.
