
PTTGC shows strong risk profile: S&P


Standard & Poor's today assigned the 'BBB' long-term corporate credit rating with a stable outlook to PTT Global Chemical Plc (PTTGC), and and 'axA' ASEAN regional scale rating.
PTTGC now assumes bonds worth US$600 million, issued equally by PTT Aromatics and Refining Plc and PTT Chemical Plc.
"The rating on PTTGC reflects the company's solid competitive position following the merger of PTTAR and PTTCH," said Standard & Poor's credit analyst Andrew Wong. "The rating also factors in PTTGC's favourable cost structure, diverse operations, and significant business integration with its parent, PTT Plc. We have also taken into consideration expected extraordinary financial support from PTT. Offsetting factors include PTTCH's exposure to inherent industry risk and price volatility, and the challenging outlook for the refining and petrochemicals industry."
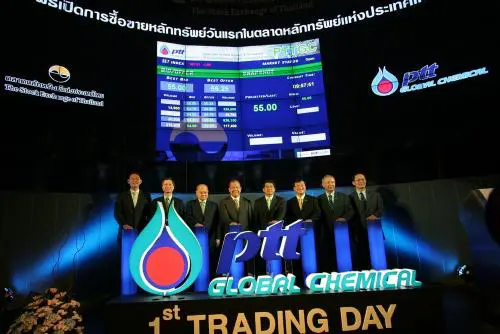
PTTGC today made a successful debut on the Stock Exchange of Thailand.
The share price ended at Bt54, higher than Bt53 which was the average of last share prices of PTTAR and PTTCH which were merged to create the Asean second largest petrochemical company.
The ratings company viewed that the merged entity's risk profile is stronger than that of both PTTAR and PTTCH.
"Our view is based on the stronger competitive position of the merged company due to its increased product diversity, operational integration, and stronger market position. Nevertheless, PTTGC's profitability is likely to be weaker than PTTCH's, given that refinery and aromatics margins are lower than in the petrochemicals business," the analyst said.
S&P expected PTTGC's financial performanceto moderate in the second half of 2011 due to the weak global economy, a potential slowdown in China's economic growth, and planned maintenance shutdowns at several PTTCH plants. These factors, together with a decline in crude prices, are likely to lower product prices, crack spreads, and sales volumes. It expects weaker operating conditions to persist through 2012.
"We anticipate that PTTGC's financial risk profile will improve over the next two years and be in line with that for the 'BBB' category despite the weaker industry outlook," said Wong. "Our expectation is based on the higher production capacity at the merged company's petrochemical and aromatics operations and its moderate capital expenditure over the next two years. As a result, PTTGC is likely to generate sufficient free operating cash flow to reduce debt."
S&P believes PTTGC will continue to benefit from its significant operational integration with and strategic ownership by PTT.
"The stable outlook on PTTGC reflects the outlook on PTT because the rating on PTTGC factors in strong support from and linkage with the company's parent," said Wong. "The rating on PTTGC is unlikely to be higher than PTT's stand-alone credit profile, which we assess at 'bbb'."
