
Funding of restoration raises doubts


Play
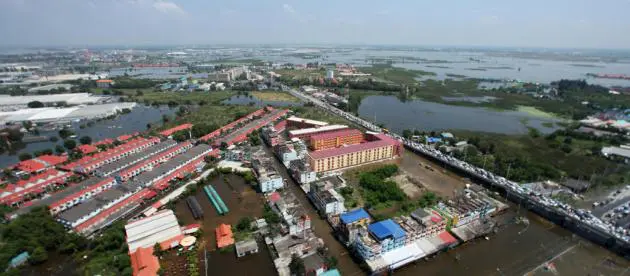
Thailand enters 2012 empasising restoration, with state agencies having to take the lead in infrastructure investment, including installing a heavyweight disaster warning system, to prevent not only floods but also other catastrophes in the future. Meanwh
The way the government plans to finance post-flood recovery projects is questionable.
Total planned public investment and loans from state and commercial banks for reconstruction is estimated to be huge, at about Bt1 trillion.
The Cabinet on December 27 approved a proposal for priority projects worth Bt17.13 billion to be implemented this year and next; Bt12.6 billion of this amount will be invested this year.
These sums were proposed by Deputy Prime Minister and Commerce Minister Kittiratt Na-Ranong.
Kittiratt, also chairman of the Strategic Formulation Committee for Water Resources Management, said investment projects included planting more forest, building new reservoirs and dykes, repairing infrastructure damaged by the severe flooding, developing a disaster database, developing the Chao Phraya River basin and compensating people affected by such development projects.
Together, these plans form part of a grand scheme to prevent future flood disasters.
The government plans to set up an investment fund for post-flood recovery worth Bt350 billion, the minister said.
To assure foreign insurers, the government will also establish an insurance pool worth Bt50 billion. This is because insurers may not dare to take risks arising from flood disasters, so the government needs to step in to share risks with private firms.
The administration will need to borrow about Bt400 billion to finance the post-flood recovery projects, according to Kittiratt.
It therefore needs to pass to the Bank of Thailand Bt1.14 trillion of overhang debt owed by the Financial Institutions Development Fund (FIDF) since the 1997 financial crisis, to lower public debt from 40 per cent of gross domestic product to 30 per cent, thus leaving much room for it to borrow more, he added.
However, the way that Kittiratt’s proposal would drag the central bank into the game has sparked a debate about the risk to fiscal and monetary discipline.
“You cannot hide public debt by shifting it to the central bank, since it is still counted as public debt, and it is the government’s responsibility to handle public debt,” said Teerana Bhongmakapat, dean of Chulalongkorn University’s economics faculty.
Meanwhile, Finance Minister Thirachai Phuvanatnaranubala has tried to pull Kittiratt back from taking an extreme position.
Thirachai said the government could not force the Bank of Thailand to pay debts against either its will or its capacity, otherwise it would mean it is ordering the central bank to print money.
Credit ratings
Printing money to pay debts could have repercussions on the country’s sovereign credit rating and banks’ credit ratings, as well as those of private firms, resulting in high borrowing costs for all parties. Credit-rating agencies are watching developments, he warned.
Nonetheless, Kittiratt’s move ties in with the position of Virabongsa Ramangkura, chairman of the Strategic Formulation Committee for Reconstruction and Future Development, appointed by the government. Virabongsa has repeatedly begged for funds from the central bank.
“The government and Virabongsa on one side, and the central bank on the other, are taking extreme positions; they need to meet half way,”
said Sompop Manarungsan, president of the Panyapiwat Institute of Technology.
Thirachai has tried to compromise by saying that the central bank could pay part of the annual interest burden of Bt45 billion. He said the bank might be able to use part of its operating profit to pay off about Bt25 billion annually.
He proposed seeking part of the funding from the Deposit Protection Agency (DPA), which supervises the fund pool collected from banks under a system designed to compensate depositors in the event of a bank run.
Virabongsa claims the country is relatively rich by pointing to the international reserves of about US$180 billion (Bt5.65 trillion), but the central bank has argued that it also has a debt obligation arising from exchange-rate operations, and that it needs to save funds to guard against rapid capital outflows caused by any uncertainty in the global market that could destabilise the country.
Kittiratt, Thirachai and Bank of Thailand Governor Prasarn Trairatvorakul agreed in principle to seek funds from the DPA, and that banks may be required to contribute fees to the FIDF. However, politicians’ efforts to get funds from the central bank are likely to continue.
If the government tries to do so, the main opposition is expected to come from followers of the late Luangta Maha Bua, a highly revered Buddhist monk, who led a campaign for gold and dollar donations for the central bank in the aftermath of the 1997 financial crisis.
Virabongsa in the past also voiced his opposition to governments trying to change account reporting at the central bank, whereby it would turn its operating loss into a profit and be required to send that profit to the government coffers.
Thirachai said he had asked Prasarn to consult Luangta Maha Bua’s followers, while he himself would also meet with them.
Late monk
The late monk and his adherents have long been the most vocal opponents of politicians trying to lay their hands on the central bank’s funds.
Meanwhile, the government has also asked the central bank to provide soft loans worth Bt300 billion to support post-flood recovery efforts. This would be on top of the previous lending target, largely involving state-run banks, of Bt325 billion.
Many economists and business leaders have called for a review of populist projects in order to save money for much-needed reconstruction spending.
Some businesspeople have called for the government to delay the planned corporate income-tax cut from 30 per cent to 23 per cent.
Teerana suggested that the government could reduce the debt burden by inviting private firms to participate in public investment.
Incorporating local communities would also help, as they have the capacity to take care of their own problems, he said.
Economists have also urged the government to increase taxes so that it can access more revenue for financing investment projects.
Indeed, a tax rise is inevitable as there is a huge debt to pay, but the government is likely to propose passing the burden on to future generations. However, taxes should be raised now, especially on polluting industries. It is the right measure, since those who contribute to global warming, a prime cause of natural disasters, should be held accountable.
