
Experts endorse central bank focus on stability


Play
The Bank of Thailand has been on the right track putting economic stability before growth, experts say. But it needs greater flexibility to manage policy-rates and the foreign-exchange market in light of rapid changes associated with monetary easing in ke
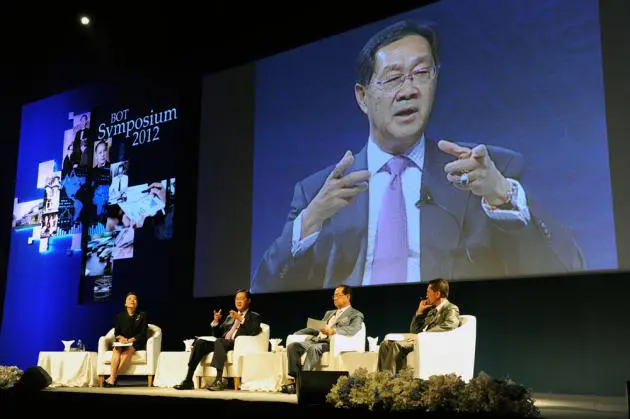
Former Bank of Thailand governor and ex-finance minister MR Pridiyathorn Devakula, and former commerce and finance minister and a member of the Monetary Policy Committee Thirachai Phuvanatnara-nubala joined a discussion yesterday as part of the BOT Symposium 2012.
They agreed losses related to foreign exchange stabilisation were not a worry and that the BOT’s inflation-targeting regime was appropriate for price stabilisation. But they were concerned about excessive lending by state banks, saying it could one day hurt overall stability in the system.
Their comments follow grave concern voiced by some officials and others in the private sector over the huge accounting losses, incurred by forex stabilisation (accumulating US dollars and the issuing of bonds with a higher rate than US rates, to absorb dollar-denominated inflows).
QE3 to spur inflows here
Supavud Saicheua, managing director of Phatra Securities, said at the symposium the US Federal Reserve’s QE3 would spur inflows to Thailand and widen BOT losses.
According to Nomura Global Economics, the baht will continue to appreciate amid more inflows. QE1 and QE2 drew US$4.1 billion to Thai market. Nomura expects the Thai baht to end the year at 30.8 per dollar, from 31.5 at the end of last year. The currency should strengthen to 30.4 next year, and hit 30 at the end of 2014.
Against concerns that increasing losses would impair the central bank’s policy options, Pridiyathorn insisted the BOT had been efficient and that losses were a result of conversion of dollar-denominated reserves to baht.
The BOT’s priority was to uphold price stability but exchange rate stability was also part of its job. As such, there should be no further debate if Thailand adopts inflation targeting or exchange rate targeting, as the BOT had taken both issues into account.
He said the public expected the central bank to be a pillar of “last resort”, with an ability to safeguard the baht and support economic growth, as well as help institutions’ to be strong.
Former commerce minister Narongchai Akarasanee also said the losses were insignificant, given they were a result of actions to keep the financial system stable. Actual losses from bond rate differentials could also be addressed and reduced, if forex intervention was kept to the minimum.
Ammar Siamwalla, chairman of the Thailand Development Research Institute’s advisory board, urged the central bank to let the baht move freely. He said policies to ease baht appreciation discouraged exporters from improving product quality and were a financial burden to the BOT. In light of greater economic complexity, he urged the central bank to work with state agencies to spur the economy.
‘Immense benefit to economy’
Narongchai said: “Inflation is not the only focus of the Monetary Policy Committee, as overall economic stability is taken into account. Aside from economic growth, we base our decision on many factors like foreign exchange rates, interest rates and bank loans.” He said the BOT had done the right thing, although at a cost.
Thirachai said the BOT should not worry about losses, as stabilisation-related losses created immense benefit to the economy. With its intervention, business people could adjust and expand operations and employment. Losses would be tackled when the growing elderly population leads to lower investment. That would weaken the baht to the point the BOT may incur profits. But he urged the central bank to clear concern on the issue and to reap higher returns from massive reserves, via investment in infrastructure projects, for example.
Thirachai did not support following Singapore in exchange rate targeting, saying imports were only 70 per cent of GDP compared to 180 per cent in Singapore. Thai competitiveness did not rely on foreign exchange rates, but price stability and access to funds.
More inflows could create bubbles in developing countries, so Thirachai urged the BOT to heighten oversight on products launched by banks’ subsidiaries before this could hurt banks financially, should any crisis happen. He suggested bi-annual talks with the Finance Ministry on the health of financial institutions.
On the health of state-owned banks, Pridiyathorn said one had borrowed heavily from Krung Thai Bank to the point that it could not finance the burden. If this continued, the country’s public debt could swell.
Thirachai said given that state-owned banks account for a quarter of the financial system, the Finance Ministry should reveal all contingent liabilities from all populist policies.
For Narongchai, state banks have been used as tools to carry out populist policies. This raised a question on what the BOT would be allowed to do if their operations created problems.
