
BOT Pledges Credit Overhaul to Open Bank Loans to Thai SMEs
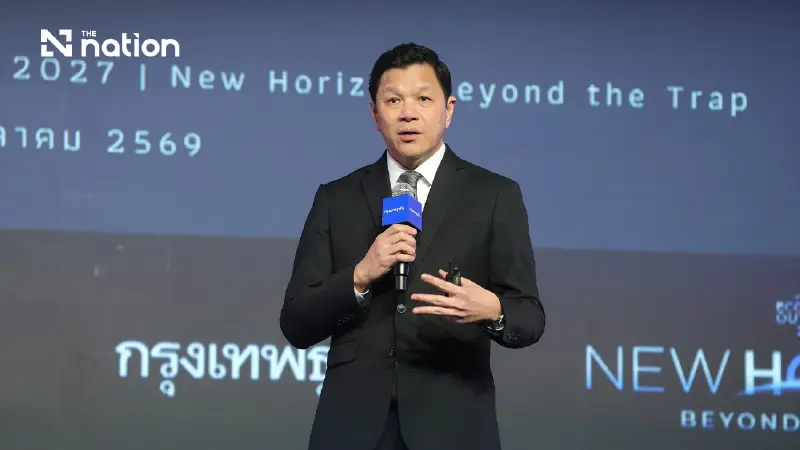


Governor Vitai Ratanakorn sets out guarantee scheme, shared data bureau and loan portal to end 16 quarters of shrinking SME credit
- The Bank of Thailand (BOT) has committed to a major credit overhaul to improve SME access to bank loans, aiming to reverse 16 consecutive quarters of credit contraction and generate 100 billion baht in new annual lending.
- The strategy is built on a three-part framework: a permanent, bank-funded credit guarantee scheme to mitigate lender risk; an alternative data exchange using government and utility records for credit assessment; and a central digital loan portal.
- Key measures include reducing costs for borrowers with free semi-annual credit bureau checks and using the new data exchange to help freelancers and online sellers without traditional payslips prove their creditworthiness.
Governor Vitai Ratanakorn sets out guarantee scheme, shared data bureau and loan portal to end 16 quarters of shrinking SME credit.
The Bank of Thailand (BOT) has committed to a comprehensive overhaul of the nation’s credit infrastructure to unlock bank lending for small and medium-sized enterprises (SMEs) and underserved borrowers.
Speaking on Thursday (Octeber 8) at the Thailand Economic Outlook 2027 forum, organised by Krungthep Turakij in Bangkok, BOT Governor Vitai Ratanakorn unveiled a three-part framework designed to tackle cost, risk, and information gaps.
Aiming to generate 100 billion baht a year in new lending, Vitai noted that if successful, the plan offers a "very high chance" of reversing 16 consecutive quarters of SME credit contraction.
Beyond Interest Rate Cuts
Vitai identified SME credit accessibility as one of four core structural challenges facing the central bank, alongside household debt, equitable access to financial services, and illicit "grey" money flows.
He stressed that monetary policy alone cannot resolve these deep-seated issues, stating that "however far the policy rate falls, it can support the economy broadly but cannot fix the 'sticky' problems that keep dragging growth lower."
While Thailand’s macroeconomic backdrop has proven more resilient than initially feared — with 2026 GDP growth projected at roughly 2.3% and exports expected to expand by 17–18% — the recovery remains acutely "K-shaped".
AI-related exports are surging by nearly 40%, yet 82% of these gains are concentrated among just 80 top exporters. Meanwhile, broader domestic consumption remains constrained by polarised household and business incomes.

The SME Credit Bottleneck
SMEs represent 99.5% of all Thai enterprises, employing 13.6 million people (nearly 70% of the workforce) and contributing roughly 35% to GDP. However, their post-pandemic recovery lags significantly behind large corporations.
The non-performing loan ratio for SMEs sits at 9.5%, compared to roughly 2% for large corporates.
Research from the BOT’s Puey Ungphakorn Institute for Economic Research (PIER) shows that even among the best-performing 30% of SMEs, only 21% can access formal credit, compared to 63% of large firms.
Consequently, 34% of SMEs rely on friends or informal lenders. The research underscores the impact of formal credit access: start-ups securing bank loans achieve a five-year survival rate of 87–93%, compared to roughly 70% for those without.
However, Vitai emphasised that credit is not a universal panacea. While the 38% of SMEs that are both profitable and growing warrant full support, businesses facing structural shifts — such as traditional merchants competing with e-commerce platforms — must adjust their business models alongside receiving financial aid.

Three Pillars to Rebuild Credit
Access The central bank’s strategy targets three core systemic frictions:
Reducing Costs: The BOT will lower identity-verification and credit-checking overheads. Under an approved rule taking effect within two to three months, data owners will receive free credit-bureau checks twice a year.
Mitigating Risk via "Credit Boost": The BOT will transition its pilot credit guarantee mechanism into a permanent five-year framework by early 2027. Crucially, the scheme is funded via commercial bank contributions to the Financial Institutions Development Fund rather than state coffers, using "not a single baht of public money."
Overcoming Information Asymmetry: An alternative data exchange will pool government, utility, and bank transaction records using National Digital ID (NDID) and the ITMX interbank network. This will allow freelancers, vendors, and online sellers without traditional payslips to prove creditworthiness.
Additionally, a central digital credit portal launching in December 2026 will allow borrowers to leverage existing collateral to seek competitive refinancing offers across multiple lenders.

Implementation Timeline and Next Steps
The reform measures will roll out over the next year: free credit-bureau checks twice annually will begin within two to three months, followed by the initial launch of the credit portal in December 2026.
In the first quarter of 2027, the portal will expand alongside the permanent launch of the "Credit Boost" guarantee mechanism. The alternative data exchange is slated for completion between mid- and late 2027.
The central bank’s strategy hinges on the premise that better data sharing and shared risk management can lower borrowing costs for viable yet underbanked firms.
Success will ultimately depend on seamless cross-agency cooperation and whether banks utilise the new risk-sharing mechanisms to expand genuine net lending rather than simply refinancing existing portfolios.
