
AI could make personalised financial advice more affordable
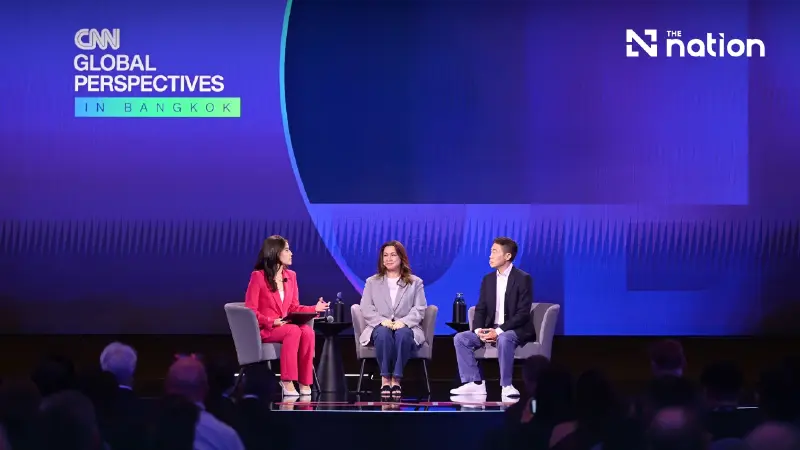


At a Bangkok forum, GCash and Growhill Wealth leaders highlight AI’s potential to expand financial services without replacing human judgement.
- AI can help financially excluded individuals establish a credit identity, providing them access to formal financial services and making guidance more affordable.
- By automating administrative and back-office tasks, which consume 50-80% of an adviser's time, AI can significantly lower the cost of delivering personalized wealth management.
- AI-powered tools, such as financial-coaching features, can offer automated guidance directly to users, reducing the need for costly assistance from bank staff.
- While AI can reduce costs and handle data analysis, human advisers remain essential for providing empathy, accountability, and understanding personal goals in financial decisions.
Artificial intelligence (AI) could open formal financial services to more people and lower the cost of personalised advice, Martha Sazon, chief executive of GCash parent Mynt, and Alan Lau, executive chairman of Growhill Wealth, told a Bangkok forum on October 14, 2026.
Speaking during the “Democratising Wealth in the Age of AI” panel at CNN Global Perspectives: In Bangkok, Sazon highlighted how technology could help people excluded from banking establish financial identities. Lau focused on reducing the cost of serving wealth-management clients while retaining human judgement and accountability.
GCash sees AI as a route to wider financial access
GCash’s Sazon identified financial access as a leading challenge in the Philippines, putting the proportion of the population with a bank account or another formal financial account at just 50%.
People outside the formal financial system often fall prey to informal lenders charging interest of up to 50% a week, according to Sazon. AI could help address that exclusion by supporting credit scoring and enabling providers to assess customers’ creditworthiness.
“AI helps disadvantaged people who cannot access financial services establish an identity and become visible. It is not just about efficiency. Once customers become visible, it becomes easier to trust them,” Sazon said.

Sazon linked that trust to giving underserved customers greater access to financial services and more control over their money.
GCash has developed an AI-powered financial-coaching feature to offer guidance to everyday users without requiring assistance from bank staff, Sazon explained. GCash brands the feature Pera Coach.
AI could reduce the cost of personalised wealth advice
Lau argued that AI could make personalised wealth management less costly to deliver, addressing a service gap that affects even affluent clients. Many high-net-worth individuals do not receive the service they should because tailoring advice to each customer is expensive, he explained.
Asia has more than one million financial advisers looking after over US$90 trillion in assets, yet advisers spend 50–80% of their time on repetitive paperwork and back-office administration, according to Lau.
Automating routine work could improve the quality of financial advice as well as reduce costs, Lau argued. Less administration would also give advisers more time to sit down with clients and understand their needs.
Lau described AI as a potential third participant in meetings between an adviser and a client, providing a logical perspective and questioning whether decisions were sound. A number of companies had already begun appointing AI board members to provide this kind of scrutiny, he added.
Human judgement remains central to financial advice
Lau stressed that financial decisions require empathy and an understanding of family dynamics and personal goals, not simply an analysis of figures. Those needs make human advisers indispensable even as AI takes on more work.
“Financial decisions often involve more than numbers and logic. They also require an understanding of clients and their families. Although AI can help in many areas, human advice will never disappear because AI lacks empathy, which is an important part of financial advice,” Lau said.
The CNN panel also highlighted cybersecurity and client confidentiality as essential conditions for using AI in financial services. Providers need to comply with personal data protection laws, use encryption, obtain customer consent and follow AI governance policies.
Transparent AI processing should allow financial advisers to verify information before making decisions, the CNN panel emphasised. Broader financial access must be built on transparency, trust and strong protection for customers.
“Although AI can do the preparatory work and gather information, it does not bear legal responsibility. When it comes to financial advice, trust in people who remain accountable is therefore the most important factor, and something people are willing to pay for,” Lau said.
