
IMF forecasts 3.1% global growth in 2026 as meetings end
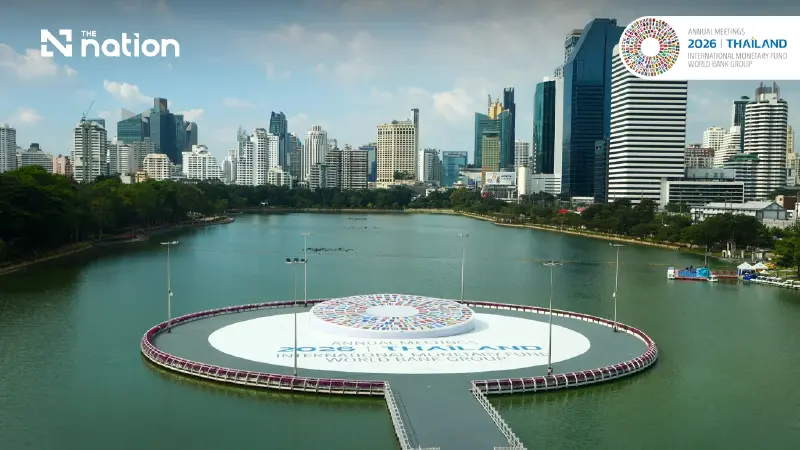


The IMF forecasts Thai growth at 2.1% as energy costs, artificial intelligence risks and public debt dominate its Bangkok meetings.
- The International Monetary Fund (IMF) projects global growth of 3.1% for 2026, a slowdown from 3.5% in 2025.
- This growth is shaped by competing forces, with investment in artificial intelligence (AI) supporting activity while an energy crisis, rising inflation, and mounting public debt act as constraints.
- The forecast reflects a highly uneven outlook, with economies tied to AI supply chains expanding rapidly while others, particularly those impacted by the Middle East war, are expected to contract.
- Downside risks to the projection are significant and include prolonged geopolitical conflict, threats to energy infrastructure, cyber threats, and extreme weather.
The International Monetary Fund (IMF) and World Bank Group Annual Meetings concluded in Bangkok on Sunday (October 18, 2026), with the IMF projecting global growth of 3.1% this year despite disruption from artificial intelligence (AI), an energy crisis and mounting debt. Thailand’s economy was forecast to expand by just 2.1%, underscoring the uneven outlook.
IMF Managing Director Kristalina Georgieva described an economy sustained by competing forces. AI investment was supporting activity, while the energy supply shock from war in the Middle East was driving inflation higher and restraining growth.
Georgieva likened the world to a single boat buffeted by technological change and geopolitical tensions, with public debt limiting policymakers’ ability to steer away from danger.
The IMF’s October 2026 World Economic Outlook projected global growth of 3.1% this year, down from 3.5% in 2025, and raised its 2027 forecast to 3.4%. The 2026 projection matched the Fund’s forecast a year earlier, although the apparently steady headline concealed increasingly divergent national prospects.
Energy crisis widens growth gaps and revives inflation
The IMF forecast a 4.8% contraction in Gulf Cooperation Council economies in 2026, reflecting the impact of the Middle East war. By contrast, economies benefiting from AI supply chains received growth upgrades, with Taiwan projected to expand by 10.7% and Vietnam by 8.4%.
The IMF reported that only 32 countries now account for 95% of global growth, down from 54 in April. Risks remained tilted towards weaker outcomes, including a prolonged war, attacks on energy infrastructure, cyber threats and extreme weather.
Higher energy and food prices were expected to push global headline inflation from 4.1% in 2025 to 4.7% in 2026, according to the IMF.
Food-price pressures have also intensified. Rice import prices have risen by 50% and wheat import prices by 37% since the Middle East war began, while a super El Niño expected to persist into the first quarter of 2027 could add further pressure.

US Federal Reserve chair Kevin Warsh reaffirmed the central bank’s commitment to price stability during a major international appearance in Bangkok on his 148th day in office. The Fed had raised its policy rate by 0.25 percentage point to 3.75–4.00% on September 16, its first increase since 2023.
Warsh declined to indicate the direction of the remaining policy meetings of 2026, describing a “new chapter for the Fed” without forward guidance. Central banks were tightening almost simultaneously, with “no free riders”, Warsh observed.
The IMF found that 14 of 33 major central banks had raised interest rates since the second quarter of 2026. Georgieva supported timely action, arguing that raising rates now was preferable to falling behind inflation and having to tighten more aggressively later.
Government borrowing costs reflected the shift. Ten-year sovereign bond yields in the United States, Germany and Japan reached their highest levels since 2002, 2009 and 1996 respectively, while long-term yields in much of Asia rose by 40–60 basis points in 2026, increasing financing costs for governments and businesses.
AI sustains growth while increasing financial exposure
Warsh described AI as potentially the most consequential economic transformation of his lifetime. The technology could deliver a “positive supply shock” in the medium term, but was currently boosting demand first, making the transition towards longer-term benefits uneven.
The IMF’s Global Financial Stability Report assessed financial stability risks as elevated and identified three channels through which leverage was increasing around AI:
- Major cloud providers’ borrowing: Their share of global investment-grade corporate bond issuance rose from less than 1% to 10% since 2024.
- Hedge funds and margin lending: Combined equity positions and margin loans increased from 10% to around 15% of advanced-economy gross domestic product (GDP).
- Leveraged exchange-traded funds: The share of single stocks in these funds rose from 16% to 28%, as retail investors used them to gain leveraged exposure to AI shares.
The IMF also identified 14 circular financing transactions among AI companies, involving about US$300 billion in equity investment and US$650 billion in debt, linked to US$1.4 trillion in commitments to purchase future services or chips.
An IMF scenario estimated that an unwinding of AI investment could directly reduce global GDP by up to 0.4% relative to the baseline by 2028. The financial stability report identified advanced Asian equity markets as particularly exposed to an AI correction, reflecting the region’s close links to the technology sector.
AI was also changing labour demand. IMF analysis of more than 40 million job advertisements in Asia found that demand for workers in occupations highly exposed to AI substitution had fallen by almost 10% before stabilising, while companies adopting AI were hiring more rapidly.
The IMF characterised the change as a reshaping of work rather than simply the elimination of jobs. Speaking at a Small AI session, Georgieva warned that routine, repetitive entry-level roles were likely to be replaced first, creating particular difficulties for young people looking for their first jobs.

Georgieva also highlighted the speed of emerging cyber threats. The interval between identifying a vulnerability and an attack had shortened from months to hours, and could soon shrink to minutes.
Public debt leaves less room to respond to shocks
Governments face rising risks with weaker fiscal defences, according to Rodrigo Valdés, director of the IMF’s Fiscal Affairs Department. Fiscal deficits in many countries were widening more than expected instead of gradually narrowing.
Valdés warned that today’s high debt levels were accompanied by higher interest costs. Public debt had been much lower during the period of elevated interest rates 15–20 years earlier.

The International Monetary and Financial Committee (IMFC), meeting on October 17, supported reducing fiscal vulnerabilities and pursuing fiscal consolidation. Georgieva called for credible medium-term fiscal plans in highly indebted countries, alongside protection for vulnerable groups.
The IMF recommended targeted assistance rather than broad price subsidies. Georgieva also pressed major economies to address global imbalances, arguing that the United States needed to save more, China to consume more and Europe to invest more.
Thailand’s 2.1% forecast trails regional growth
The IMF projected Thai growth of 2.1% in both 2026 and 2027. Although the 2026 figure was an upgrade from 1.5% in April, Thailand remained the weakest performer in the Fund’s five-country Association of Southeast Asian Nations (ASEAN) grouping, known as ASEAN-5.
The ASEAN-5 growth forecast of 4.4% for 2026 was more than twice Thailand’s projected rate.
The IMF also expected Thailand’s current account to move from a surplus of 3.0% of GDP in 2025 to a deficit of 1.2% in 2026 because of higher energy import costs. Thai inflation was forecast to rise from minus 0.1% to 2.1%.
The IMF publication Shaping the Future of Asia, launched on the meetings’ opening day, placed Thailand alongside Japan, South Korea and China among economies with declining working-age populations. Thailand and Vietnam faced the risk of growing old before becoming rich.
The publication assessed Thailand’s AI readiness as moderate, with a fuller transition towards AI expected during the 2030s and 2040s. The assessment suggested that the economic drag from ageing would arrive before the full benefits of technological adoption.

Bank of Thailand Governor Vitai Ratanakorn remained more optimistic about the immediate outlook, expecting growth of around 2.3% in 2026. Vitai cited projected export growth of 17–18%, alongside growth of around 13% in private investment and foreign direct investment.
Vitai nevertheless acknowledged that Thailand’s potential growth had fallen to around 2.7%. Structural constraints included decades of insufficient investment, declining productivity, a shrinking workforce and household debt equivalent to around 86–87% of GDP.

Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas argued that investment-led policies could lift growth above the IMF’s forecast. The government and private sector were pursuing a “3% plus” ambition, although Ekniti did not commit to achieving it in 2026.
“We are trying to achieve it as quickly as possible,” Ekniti replied when asked whether the target could be reached this year.
Thailand highlighted fiscal discipline as a relative strength, with public debt at around 60% of GDP, compared with levels approaching 100% in several Western economies. The increase in Thai 10-year government bond yields was also much smaller than in the United States.
Applications for foreign investment promotion rose by 47% in the first half of 2026, supported by production relocations in AI-related industries, smart electronics and electric vehicles. Translating those applications into actual investment remained central to Thailand’s growth ambitions.
Bangkok meetings produce cooperation on fraud and investment
The October 12–18 meetings at the Queen Sirikit National Convention Center attracted almost 20,000 participants from 191 countries. Ekniti described the attendance as the highest in the meetings’ history, as Thailand returned as host for the first time since 1991.
Georgieva praised Thailand’s hospitality, while IMFC chair Mohammed Al-Jadaan said the country had set a very high standard for future hosts.
Thailand’s policy and cooperation outcomes included:
- Bangkok Blueprint: The Bank of Thailand developed the five-pillar framework, containing 12 considerations, with the IMF and World Bank Group to combat cross-border digital financial fraud and disrupt illicit financial flows. IMFC members supported the initiative. Thailand’s reported fraud losses exceeded 43 billion baht in 2024 and 9 billion baht in the first half of 2026, while global losses were estimated at around US$1 trillion annually.
- More than 50 bilateral engagements: Cooperation included a signed double taxation convention with Norway, capital-market cooperation with Luxembourg, discussions with the World Bank and Asian Development Bank (ADB) on water management in the Chao Phraya and Pa Sak river basins, and an ADB agreement to support hospitals preparing for an ageing society.
- Low-carbon financing: The World Bank provided a US$200 million lending facility through the Export-Import Bank of Thailand under the Low Carbon Cities programme. Krungthai Bank and the Stock Exchange of Thailand were involved in developing a carbon-credit trading mechanism.
- “Trusted Connector” strategy: Thailand promoted its role as a link between major powers and smaller economies through the Laos–Thailand–Malaysia–Singapore clean-energy network, the ASEAN Digital Economy Framework Agreement and free trade negotiations with European partners.
Interest rates and AI investment lead the post-meeting watchlist
The remaining US monetary policy decisions, the durability of AI investment and the path of energy prices will help shape the economic outlook after the Bangkok meetings. For Thailand, investment delivery and fiscal reform will also determine whether stronger growth ambitions become achievable.
Five developments warrant attention:
- Global interest rates: Two Federal Open Market Committee meetings remain in 2026. Without advance policy guidance from the Fed, markets face greater uncertainty, with implications for the baht and decisions by the Bank of Thailand’s Monetary Policy Committee.
- AI investment risks: Technology companies’ bond issuance, market leverage and actual AI earnings relative to expectations will be important indicators, particularly for Asian equity markets tied to AI supply chains.
- Energy and food prices: The duration of the Middle East war and El Niño will influence business costs and Thailand’s current account.
- Thailand’s growth ambitions: Moving from the IMF’s 2.1% forecast towards growth above 3% will depend partly on how quickly investment applications become realised spending and how extensively Thai small and medium-sized enterprises join the resulting supply chains.
- Fiscal reform and disclosure rules: Areas to watch include Finance Ministry plans to reduce overlapping expenditure, use AI to improve tax collection and tax foreign e-commerce platforms, alongside sustainability disclosure requirements for listed companies.
Before the meetings ended, Georgieva said the IMF would take the words of His Majesty King Bhumibol Adulyadej the Great back to Washington: benefits and positive outcomes do not emerge by themselves, but must be gradually cultivated, accumulated and strengthened over time.
