
Bank of Thailand Denies Rift With Chair, Rejects Central Bank Law Change
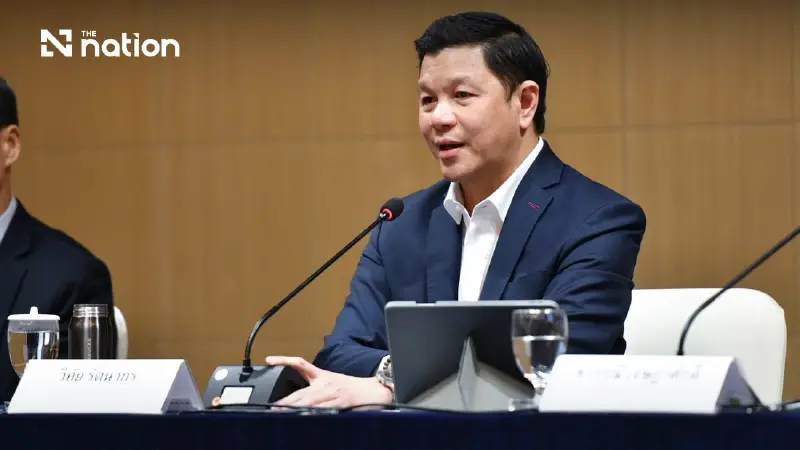


Governor Vitai Ratanakorn says the law meets global standards as the central bank turns to tighter regulation of non-bank lenders
- Governor Vitai Ratanakorn held a press conference to deny any internal conflict with Chairman Somchai Satjapong, who had publicly criticized the bank's performance.
- The Bank of Thailand (BoT) firmly rejected proposals to amend the central bank law, arguing the current legislation meets global standards and the suggested changes would threaten its independence.
- Instead of altering its own law, the BoT will seek to amend the Financial Institutions Business Act to tighten regulatory oversight of non-bank lenders.
Governor Vitai Ratanakorn says the law meets global standards as the central bank turns to tighter regulation of non-bank lenders.
The Bank of Thailand (BoT) moved on Monday (November 16) to quell speculation of a leadership rift, denying any internal conflict with its board and affirming its respect for Chairman Somchai Satjapong, while firmly ruling out amendments to the central bank law.
Governor Vitai Ratanakorn called an urgent press conference at BoT headquarters, flanked by senior executives, in response to a five-page statement released by Somchai on 14 November criticising the bank's performance.
Vitai stated that a comprehensive review of the BoT Act—conducted with external board members and key financial regulators—concluded the current legislation remains modern and aligned with international standards.
Instead of altering the BoT Act, the central bank will push to amend the Financial Institutions Business Act to tighten oversight of fast-growing non-bank lenders and enhance consumer protection.
The Chairman’s Criticisms
Somchai, who assumed the chairmanship on 2 June 2025, accused the central bank of failing to update the laws under its purview over the past 18 months, noting it had proposed amending only a single section of the Financial Institutions Business Act.
He also faulted the BoT for failing to reverse a contraction in small and medium-sized enterprise (SME) lending spanning 17 consecutive quarters.
Citing research on capital misallocation, Somchai questioned whether the central bank had been overly lax in supervising—and effectively protecting—commercial banks.

Vitai explained that a public response was necessary because the proposed changes threatened the central bank’s independence and checks and balances.
Compromising those principles, he warned, would directly erode confidence in both the BoT and Thailand's financial system.
Timeline of the Legal Review
Deputy Governor Suwannee Jatsadasak outlined the timeline of the legislative review, which state agencies are legally required to conduct every five years:
• Mid-2025: The BoT assessed the BoT Act—overhauled in 2008 and amended in 2016, 2017, and 2018—and held a public hearing, finding it remained fit for purpose.
• 25 June 2025: The board, chaired by Somchai, merely acknowledged the report without ordering any changes, after which it was submitted to the finance minister.
• October 2025: Somchai requested a review of the act via an external working group. However, a majority of directors favoured an internal study first. The resulting internal working group polled every board member—including ex officio leaders from the National Economic and Social Development Council, the Fiscal Policy Office, the Securities and Exchange Commission, and the Council of State—and received zero proposals to amend the BoT Act.

Four Rejected Proposals
The working group evaluated four informally raised proposals against international central banking laws and advised against all of them:
• Tying performance targets to governor dismissal (Sections 25 and 28/19): Mirroring laws in Britain, Norway, and Malaysia, the BoT Act separates performance reviews from removal criteria to prevent political or vested interests from weaponising unrealistic targets during policy disputes.
• Expanding the board's role in selecting the governor: Reforms in 2008 and 2016 established an independent selection committee free of politicians and civil servants to insulate the appointment process.
• Barring the governor from nominating expert directors: The law separates nominators (the governor and the Finance Ministry’s permanent secretary) from the selection committee, recognising that the governor best understands the bank's operational needs.
• Downgrading the governor from board deputy chair to secretary: The governor serves as deputy chair to integrate monetary policy, financial supervision, and payment systems. Most major economies—including the US, Germany, Australia, and Japan—appoint the governor as board chair; none reduce the role to secretary.
Shifting Focus to Non-Banks
While leaving the BoT Act untouched, the working group identified an urgent need to overhaul the Financial Institutions Business Act.
Non-bank entities now play a major role in personal loans, vehicle-title loans, credit cards, nano-finance, payment services, and asset management, yet their supervision still relies on Revolutionary Party Announcement No. 58 from 1972.
The BoT plans to expand its regulatory authority under the Financial Institutions Business Act to apply risk-based oversight across all credit-like activities to prevent public exploitation.
Addressing Economic Concerns
Vitai also pushed back against criticisms regarding the bank's economic management:
• SME Lending: Attributing the 15-to-17-quarter slump to structural economic headwinds rather than central bank legislation, he highlighted active BoT interventions. These include the SME Secure+ scheme and SME Credit Boost, which diverts 20 billion baht from commercial banks’ Financial Institutions Development Fund contributions to back up to 80 billion baht in loan guarantees.
• Commercial Bank Oversight: Rejecting claims that the BoT shields lenders, Vitai said supervision is at its strictest. Alongside the 20-billion-baht SME diversion, the bank cut 19 banking fees, trimming sector revenue by over 8 billion baht. Third-quarter banking profits in 2026 fell 9% year-on-year.
• Grey Money Curbs: New withdrawal limits have sharply curtailed illicit financial flows. Cash withdrawals exceeding 5 million baht plunged 69% (from roughly 100 billion baht to 30 billion baht), while gold bullion withdrawals over 2 kilogrammes dropped 85% compared to January 2026. The BoT continues to monitor for transaction splitting aimed at evading these thresholds.
Communication Breakdown
Addressing his personal rapport with the chairman, Vitai revealed the two had not spoken directly since the dispute erupted.
He sent an explanatory message via LINE as soon as he learned of Somchai's dissatisfaction, but the chairman—who was travelling overseas—did not read it for roughly 10 days and has yet to reply.
The two last spoke normally at a royal ceremony on 6 November, and a subsequent meeting was cancelled due to Somchai's overseas travel.
"There is no conflict within the Bank of Thailand, either among the executives or between us and the board," Vitai reiterated. "We continue to respect the chairman, and I will ask to meet him to talk things through as soon as the situation allows."
