
Bank of Thailand reports progress on debt relief and SME lending
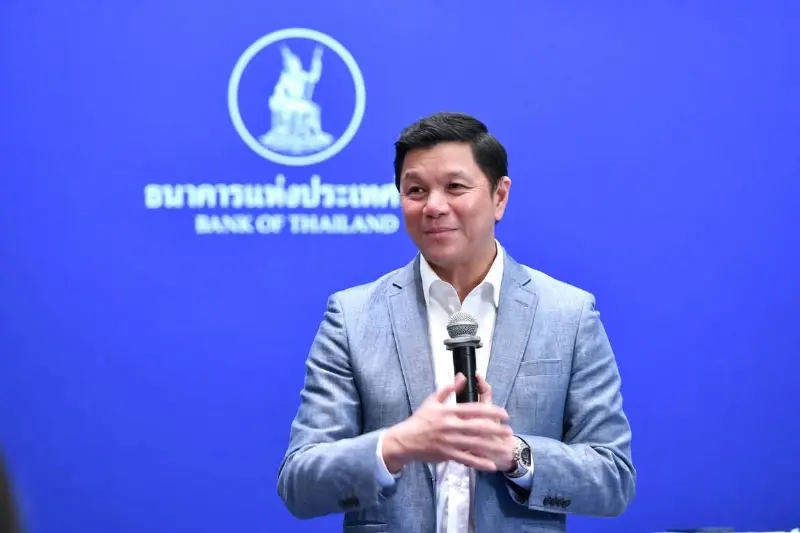


Governor Vitai Ratanakorn stresses sustained action on structural problems, with comprehensive oversight of non-bank financial businesses planned for 2027.
- The Bank of Thailand (BOT) has restructured over 180,000 non-performing retail debt accounts under its "Clear Debt Fast, Move Forward" programme to address household debt.
- To provide further debt relief, the central bank has kept the minimum credit card repayment rate at 8% for approximately 2 million accounts.
- For small and medium-sized enterprises (SMEs), loans totaling more than THB 80 billion have been issued under the "SMEs Credit Boost" programme.
- The BOT is improving SME access to credit by allowing alternative collateral and preparing to launch an "SMEs Credit Portal" to connect businesses with lenders.
- The bank has also reduced or abolished 19 financial service fees, saving retail customers and SMEs an estimated THB 8 billion annually.
Bank of Thailand (BOT) governor Vitai Ratanakorn has posted a review of the past year's work, stressing that structural problems require sustained action and cannot be resolved through a single programme or by one agency.
He emphasised that addressing these problems must involve practical action, beyond analysis or publicity.
The BOT continues to fulfil its core responsibilities for price stability and the stability of the financial institution and payment systems.
It has also expanded its role in supporting the economy and addressing structural problems amid an uneven recovery.
Over the past year, the central bank revised its strategic direction and pursued an accommodative monetary policy, cutting the policy interest rate twice from 1.50% to 1.00%.
It also managed the exchange rate to reduce volatility and introduced 18 targeted measures covering four areas: household debt, credit access for small and medium-sized enterprises (SMEs), fair treatment of financial services users, and the prevention of illicit money flows and corruption through the financial system.
To address household debt, the BOT and Sukhumvit Asset Management (SAM) have restructured more than 180,000 non-performing retail debt accounts under the “Clear Debt Fast, Move Forward” programme, against a target of 200,000 accounts for 2026.
The central bank has also kept the minimum credit card repayment rate at 8% to help preserve liquidity for borrowers with around 2 million accounts.
For SMEs, loans totalling more than THB80 billion have been issued under the “SMEs Credit Boost” programme.
“SMEs Secure Plus” has helped improve liquidity by allowing financial institutions to consider other collateral alongside business cash flow.
The BOT is also preparing to launch “SMEs Credit Portal” in January 2027 to connect businesses with lenders, with plans to use alternative data to help financial institutions assess business potential more comprehensively.
The BOT has reduced or abolished 19 fees across financial services, including deposit accounts, electronic cards, payment transactions and SME lending.
These changes are expected to save retail customers and SMEs around THB8 billion a year.
To prevent illicit money flows, the BOT has tightened customer screening and identity verification, monitored suspicious transactions and required gold transaction reporting in line with the criteria specified in its measures.
It has also developed a framework to protect the financial sector from illegal activities and worked with the International Monetary Fund and the World Bank Group to advance the Bangkok Blueprint.
Work planned through March 2027 includes regulating cash purchases and sales of gold worth more than THB10 million, supervising buy now, pay later (BNPL) services, reducing credit bureau check fees, regulating baht stablecoins and raising standards for money-changing businesses.
In 2027, the BOT will place emphasis on tackling household debt and expanding SME access to credit through the Credit Portal, credit guarantee mechanisms and Alternative Data Exchange.
It also plans comprehensive oversight of non-bank financial businesses, covering lending, payment services, currency exchange, money transfers and asset management companies, to protect customers and ensure fair treatment in financial services.
