
Thailand Needs Better Drivers, Not Just New Engines, Panel Hears
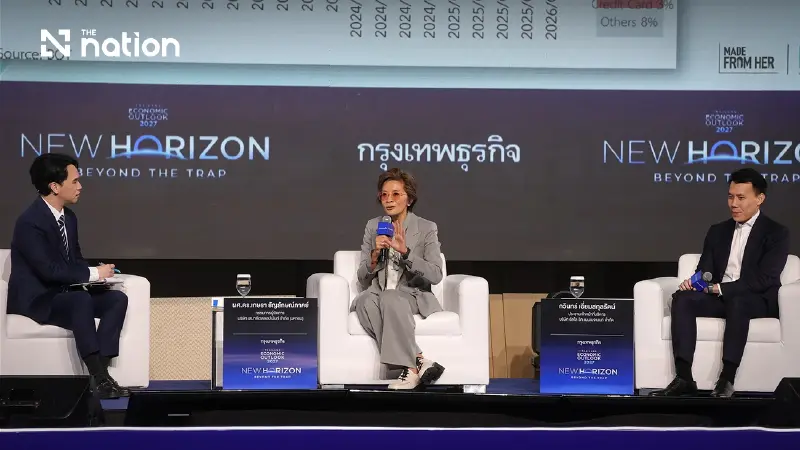


Two property chiefs say an ageing, indebted Thailand must lift income and output per worker through AI, green investment and new business models
- Business leaders argue that new economic "engines" are of little use if the "drivers"—the Thai people and institutions—are not ready, citing constraints like an ageing society and a shrinking workforce.
- The "drivers" of the economy are hampered by high household debt, which limits their ability to consume and invest; the proposed solution is to increase people's earning power rather than just offering debt relief.
- To create "better drivers," the panel recommends increasing productivity per worker through the widespread adoption of tools like AI and technology, enabling a shrinking workforce to generate more economic value.
Two property chiefs say an ageing, indebted Thailand must lift income and output per worker through AI, green investment and new business models.
Thailand's economic challenge is no longer just finding a new engine of growth but building the capacity of the people and institutions that must drive it, two property-sector executives told a business forum on Thursday (October 8).
Speaking at Thailand Economic Outlook 2027: New Horizon Beyond the Trap, hosted by Krungthep Turakij, they addressed the theme "New Driving Force for Thailand's Second Take-off".
Kessara Thanyalakpark, managing director of Sena Development, and Kavin Eiamsakulrat, chief executive of ALLY REIT Management, started from the same pressures: an ageing society, a shrinking workforce, heavy household debt and years of weak growth.
Both concluded that the old formula of adding people, projects and branches will no longer work and that growth must come from creating more value per person.
The driver, not just the engine
Kessara used a car metaphor. A powerful engine is of little use if the driver is not ready, she said, and Thailand's economy is still moving but without full acceleration. The constraint, in her view, is demographic.
About one in four Thais is now elderly, she said, and the share is likely to rise to one in three in roughly 15 years, while births continue to fall.
The effect reaches beyond the labour market to the tax base, fiscal burdens and public policy. In short, Thailand has fewer people of working age while the burden of driving the economy grows.

She called for a more proactive population policy and pointed to Singapore as a country that has tackled low fertility seriously. Without early action, she warned, demographics could become friction that stops the economy accelerating, however much new fuel or new engines are added.
Household debt: a harder problem than 1997
Kessara described household debt as, in some respects, harder to resolve than the 1997 financial crisis. Back then, much of the debt sat with companies that had financial statements and accounts that could be examined.
Household borrowing is spread across millions of people, none of whom has a clear "balance sheet", which makes system-wide restructuring more complex. The data she presented also showed that high debt relative to income is not confined to the groups many assume.
It is concentrated among managers, academics, professionals and office workers. The middle class, long seen as a pillar of consumer spending, is itself constrained by debt.
Debt "haircuts" may offer short-term relief, she said, but lasting solutions require raising people's earning power. Otherwise, new borrowing will follow.
The question, she said, should shift from how much debt to cut to how to make Thai incomes grow enough. Weak incomes limit consumption and also households' ability to invest in their future, tying the debt problem directly to the engine problem.
Green investment that pays for itself
Kesara argued that the green transition must make economic sense for households. Switching from petrol cars to electric vehicles, she said, can cut travel costs per kilometre by two to three times, making EVs a way to lower the cost of living as well as an environmental choice.
The benefit would be fully realised only if Thailand builds the supply chain at home, she added, and the state has a role in designing support that creates domestic value.
She gave solar panels as a second example. A 3-kilowatt system costing about 90,000 baht could be financed at around 1,600 baht a month, she said. If the electricity savings cover the instalment, the household is better off from day one.
The task is to widen access to finance and technology. For business, she highlighted direct power purchase agreements (PPAs) between private parties. Unlocking them would open clean electricity to office towers and tall buildings that use a great deal of power but have little roof space.
From selling homes to providing housing
With consumers' buying power shifting, Kessara said property developers cannot rely on the old model. Sena proposes redefining itself from a "home seller" to a "housing service provider", so people can reach a range of living arrangements without starting with a large loan and a 30-year mortgage.

Low growth is the disease
Kavin framed the problem as one of long-running weak growth. The economy, he said, has expanded below its potential for more than a decade, and high household debt is better seen as a "symptom" than the underlying illness.
When growth is low and borrowing costs are higher, debt becomes a heavier burden, and cutting it alone does not fix the equation. If incomes cannot outpace financing costs, the debt cycle can return.
Established growth engines are also under strain, he said. Tourism, long a pillar, is showing saturation and overcapacity in some areas. Thailand therefore cannot rely simply on persuading people to spend more.
It must create new economic value. Fewer workers, more value With the workforce shrinking, he said, growth through added headcount is becoming harder, and productivity per worker could be decisive for Thailand's next phase.
The new equation, as he put it, is fewer people creating more value. The answer, he said, is not harder work but better tools. Technology should let one person do what once took many, or do existing work faster and to a higher standard.
He said AI and new technology should be spread widely across industry, agriculture, tourism and small businesses. The test is not which organisation adopts AI first but how much it raises output per worker.
If technology lets small and medium-sized enterprises (SMEs) expand without adding costs and staff in proportion, he said, they can scale in a way that was once out of reach.
The same thinking applies to property, where he said the measure of growth should shift from the number of projects or branches to how much more value existing assets can generate.
For a developer, that means making each square metre earn more by matching it to changing consumer behaviour. He described this as a move from "Growth by Expansion" to "Growth by Value Creation", a better fit for an era of higher costs and a population that is no longer growing as it once did.
Recycling capital through REITs
Kavin also highlighted real estate investment trusts (REITs) as a way to "recycle capital". By placing assets into a REIT and releasing the cash, developers can reinvest more quickly in new projects, putting money tied up in old assets back to work.
The two executives offered different tools but a shared diagnosis. Thailand is ageing, its workforce is shrinking, households are heavily indebted and growth has stalled, and none of that can be solved by the formulas of the past.
Kessara focused on the foundations: preparing people through population policy, raising incomes so debt does not simply recur, and directing investment into projects that cut living costs.
Kavin focused on the mechanics: using AI and technology to lift productivity, helping SMEs scale and freeing capital through instruments such as REITs.
As Kavin summed up, Thailand cannot grow with the old formula any more. With the number of workers unlikely to rise, he said, higher output per person has become the engine the economy needs.
