
Georgieva warns debt and AI deepen global economic divides
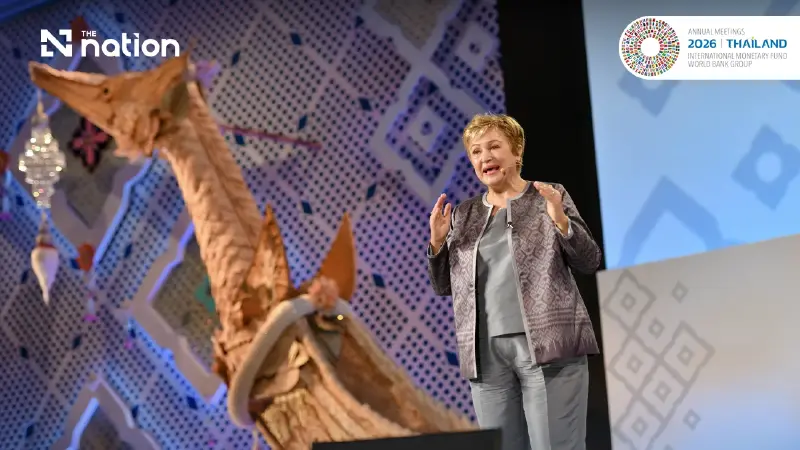


At the IMF–World Bank plenary in Bangkok, Kristalina Georgieva warns that 3.1% growth masks mounting debt, inflation and AI risks, calling for urgent reform.
- The IMF warns that high public debt and rising borrowing costs are straining government finances, disproportionately affecting low-income countries by reducing funds available for development.
- Economic gains from artificial intelligence are being unevenly distributed, with nations integrated into the AI value chain seeing growth upgrades while other economies fall behind.
- IMF Managing Director Kristalina Georgieva has urged governments to rebuild their financial buffers and implement credible fiscal plans to manage the heavy burden of public debt.
- Beyond creating economic disparity, AI introduces new risks such as severe cyber threats and potential financial instability, necessitating stronger international cooperation.
The International Monetary Fund (IMF) has urged governments to rebuild their financial buffers and curb rising debt, warning that steady global growth is masking inflationary pressures, geopolitical disruption and uneven gains from artificial intelligence (AI).
Speaking at the plenary session of the 2026 IMF–World Bank Annual Meetings in Bangkok on Friday (October 16), IMF Managing Director Kristalina Georgieva said the world economy remained on course to grow by 3.1% this year, matching the Fund’s forecast from October 2025, despite a difficult international environment.
An energy supply shock was weighing on economic activity, while investment linked to AI was providing an offsetting boost. But the benefits were distributed unevenly: conflict-affected economies had suffered substantial downward revisions to their growth outlooks, while the US, China, India and other mostly Asian economies integrated into the AI value chain had received upgrades.
Georgieva opened by thanking her Thai hosts, including Prime Minister Anutin Charnvirakul and Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas. She also acknowledged World Bank Group President Ajay Banga and Carlos Carvallo Spalding, president of the Central Bank of Paraguay and chairman of this year's Annual Meetings.
Pointing to a replica of Thailand’s Royal Barge, she drew a comparison with countries navigating global uncertainty together.
“Today, our boat is being lashed by the waves of technology and geopolitics. Our ability to twist and turn and manoeuvre is impaired by a heavy load of public debt,” she told delegates.

Rising borrowing costs add to fiscal pressures
High public debt was reducing countries’ capacity to respond to shocks, Georgieva warned. Advanced economies had accumulated particularly heavy debt burdens, while debt was also rising in emerging markets. Many low-income countries faced increasing interest bills and declining official aid, even where their debt-to-GDP ratios were comparatively lower, leaving less money for development.
Inflationary pressures were fuelled by energy supply disruptions, threats to shipping routes and shortfalls in refining capacity and natural gas supplies. Northern countries needed to rebuild fuel reserves before winter, while the infrastructure required for AI was creating additional demand and was increasingly financed through borrowing. A “Super El Niño” was also putting pressure on food prices, with poorer households particularly exposed.
Yields on ten-year government bonds in the US, Germany and Japan had recently reached their highest levels since 2002, 2009 and 1996 respectively, she reported. Higher benchmark yields were raising financing costs in other economies too, especially those carrying more debt, although financial market conditions remained orderly.
Given the risk of persistent inflation, Georgieva supported the recent monetary tightening and firm signals from the US Federal Reserve, European Central Bank and Bank of Japan. She cautioned that delayed action could force central banks to increase interest rates more sharply later.
For heavily indebted governments, stronger growth alone would not be enough to reverse the upward debt trend quickly. She called for credible medium-term fiscal plans, accompanied where necessary by early measures to reduce deficits.
“Policymakers need to explain why it is necessary. They need to formulate plans that limit costs to future growth. They need to protect the most vulnerable in society,” she stressed.
These policies should be supported by structural reforms that improve long-term growth prospects. She placed particular emphasis on large advanced economies, whose fiscal choices could have consequences well beyond their borders.

AI growth brings new risks and responsibilities
Georgieva described the pace of technological change as exceptional, citing advanced robotics, quantum computing, cloud technology, financial technology and medical advances alongside AI.
She recognised AI’s potential to boost productivity and extend access to useful services, including through ordinary smartphones, but cautioned that the speed and scale of productivity gains remained uncertain.
Countries would need different preparation strategies depending on whether they developed AI technology, supplied inputs or mainly adopted it. Policymakers also had to address potential youth unemployment, erosion of tax revenues, financial instability and increasingly severe cyber threats.
She warned that the interval between the discovery and exploitation of software vulnerabilities was shrinking from months to hours and could soon fall to minutes. Because cyber failures could spread across borders, stronger national financial supervision and international collaboration were essential.
“A borderless global AI system may only be as strong as its weakest link,” she warned, calling for urgent and practical cooperation to ensure technological progress benefited people everywhere.
IMF calls for reforms in US, China and Europe
Turning to global economic imbalances, Georgieva urged the US to save more, China to increase consumption and Europe to invest more.
She called for fiscal consolidation in the US, reduced state involvement in economic decisions and stronger social safety nets in China, and greater economic integration within the European Union.
In the near term, however, she saw little movement in the required direction, with the US still heavily dependent on domestic demand and China on net exports.
The IMF had completed comprehensive reviews covering economic surveillance, lending conditionality and methods used to assess debt sustainability in low-income countries.
Its financial-sector work included approximately 300 technical assistance and training programmes in financial supervision and 15 Financial Sector Assessment Program exercises each year, aimed in part at improving resilience against cyber threats.

Georgieva presses members to support the poorest countries
IMF credit outstanding and undrawn loan commitments totalled around US240billion,Georgievareported,whileremaininglendingcapacitywasaboutthreetimesthatamount.ConcessionallendingreachedUS36 billion, around four times its historical average.
She appealed for further backing for the Poverty Reduction and Growth Trust (PRGT), the Fund’s main concessional lending mechanism for low-income members.
Assurances from 39 countries had brought the level of support to about 48%. Efforts by European Union countries could lift the figure to 74%, still below the 90% target.
“For the sake of our most vulnerable members, let’s get this done,” she urged.
She also announced that more than US$100 million in fresh commitments for IMF capacity development had been secured during the Bangkok meetings, equivalent to approximately one-quarter of the Fund’s annual spending on those activities.
Concluding with a reference to the late King Bhumibol Adulyadej, Georgieva stressed that lasting improvements had to be built patiently rather than being expected to emerge on their own.
Despite the obstacles ahead, she argued that the world remained on a path towards improvement, but favourable outcomes could not be taken for granted. Collective effort among all 191 IMF members was essential to delivering better lives for people around the world.
