
Village funds open to abuse, NPLs 'quite high'


Play
If fund was not properly managed it would not have lasted 12 years, says official
The government has spent more than Bt77 billion over the past two years on its four key populist projects. However, some experts have cast doubts on the official percentage of non-performing loans (NPLs) generated by the funds, saying the real figure is much higher.
The four funds in question include the National Village and Urban Community Fund, the Village and Community Capacity Development Fund, the Women Empowerment Fund and the Urban Development Project.
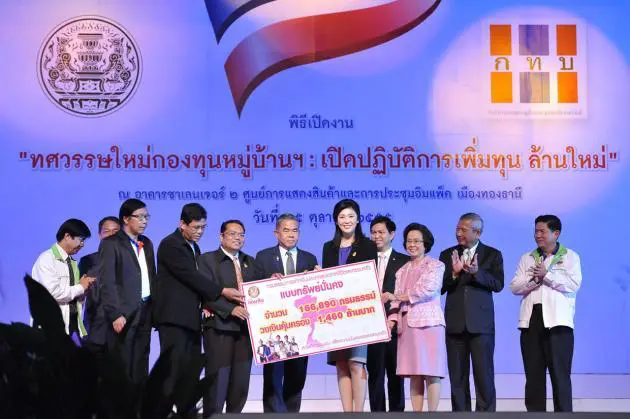
So far, the Yingluck Shinawatra government has allocated Bt44.7 billion of the Bt79.2 billion it earmarked for the National Village and Urban Community Fund, and given Bt29.8 billion of the Bt30 billion it set aside for the Village and Community Capacity Development Fund. The Women Empowerment Fund has received Bt3 billion of the Bt7.7 billion allotted for its 39,586 projects, while the Urban Development Project has received Bt16.1 million.
Since the National Village and Urban Community Fund went into operation 12 years ago, it has accrued Bt10 billion in NPLs and another Bt62 billion in pending loans. The government will assess the other funds next month.
Natee Khlibtong, CEO and secretary-general of the National Village and Urban Community Fund Office, said these four funds did not overlap as each had its own specific purpose. He explained that many villagers sought loans to purchase agricultural tools and materials, even though some critics have been saying that farmers borrow money to purchase unnecessary items like mobile phones, pick-up trucks and motorcycles.
“If the village fund was not properly managed, it would not have lasted for 12 years. There is Bt206 billion revolving in the fund at present, and if it had not been managed well enough, it would have been lost. Sixty to 70 per cent of the money is still available, with the level of NPLs at no more than 5 per cent,” he said.
He went on to explain that the high level of NPLs was based on a difference in accounting criteria. For instance, he said, the Comptroller-General’s Office turns a loan into an NPL from the first day that a borrower fails to finance the interest. The fund, on the other hand, does not change the loan’s status if the borrower asks for an extension on repayment.
Natee said that legal action was being taken against those who were refusing to pay back. More than 5,000 cases are currently in court with Bt400 million at stake – a small sum compared to the fund’s total value of more than Bt200 billion.
As for irregularity in the accounting, he said some of it could be blamed on the people who are asked by villagers to submit project plans on their behalf. He said these project writers are usually local government officials or those who are closely related to members of the fund committee. Also, he said, officials found to be irresponsible would not be selected as committee members.
Somchai Jitsuchon, research director for macroeconomic development at the Thailand Development Research Institute, meanwhile, expressed concerns about how the money was being spent and what impact it was really having despite the so-called promise of a low-interest loans for poor people.
Instead, he said, the government was in a better position to explain why so many funds were needed and what tangible benefits they had. He also questioned whether those seeking SML loans truly represented the local community as he cited research that less than half of the villagers seeking loans had truly benefited over the past decade.
Somchai also questioned the 5-per-cent NPL figure, asking how non-performing loans were calculated. For instance, he said, some villagers borrowed from loan sharks to pay what they owe the village fund – a move that would keep the number of NPLs artificially low and allow them to become eligible for a government loan the following year. “The real NPL figure is most probably between 30 and 40 per cent,” Somchai said, as he called on people to monitor various government funds and find out how they are being used and repaid.
