
Developers seek ways to cut mortgage rejection rates


Play
Building up a financial history for non-salary earners among measures some leading firms and banks have homed in on
Property firms have been negotiating with commercial banks over possible ways to reduce the rejection rate for mortgage applications during a period in which the banks have tightened the lending criteria for what they consider to be risky customers.
The Bank of Thailand has warned commercial banks to restrict loan provision and increase their loan-loss reserves in light of the additional risk inherent in the country’s slower economic growth and the impact of heightened political uncertainty.
Most commercial banks have restricted the provision of mortgages among home-buyers with a low income and who do not have a history of bank transactions, as well among those who are freelance workers or entrepreneurs that do not have a regular monthly income.
As a result, the average rejection rate for housing-loan applications has increased from 25 per cent to between 30 and 35 per cent, although some banks have a rejection rate of up to 50 per cent due to their more stringent lending criteria.
Meanwhile, the banks have revised the loan-to-value ratio from an average of 95 per cent for low-rise residences such as detached houses and town-houses to between 80 and 90 per cent, depending on each customer’s purchasing power.
They have also adjusted the loan-to-value ratio from an average of 90 per cent for condominium projects, to just over 80 per cent.
“We have adjusted the loan-to-value ratio for customers who buy a third or fourth home to 85 per cent, and also have a rejection rate of about 50 per cent. This is in line with customer risk, because some of them have a debt burden greater than their ability to repay,” said Kasikornbank executive vice president Pakorn Partanapat.
With the current market environment directly impacting property firms if they find they are unable to transfer homes to customers, developers have been seeking ways to help home-buyers get a loan.
Help for those without a salary
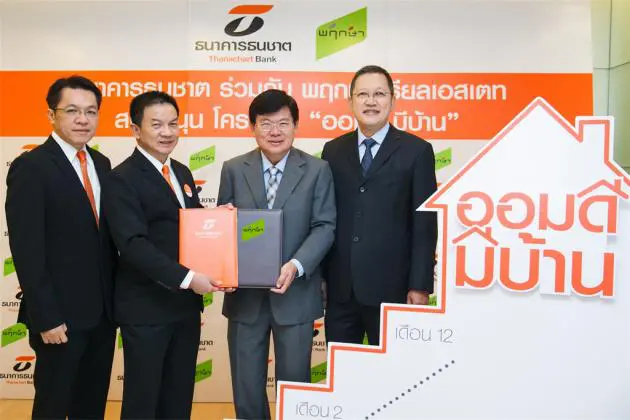
For example, Pruksa Real Estate, whose customers face a rejection rate of between 20 and 25 per cent, has joined forces with Thanachart Bank to launch the “Oam Dee Mee Baan” (Have savings, have a home) campaign.
The campaign will support freelance and entrepreneur customers without a monthly salary but who can show sufficient financial statements, to get a housing loan.
Customers have to open a deposit account at Thanachart Bank, and make monthly savings instalments over a period of 12 months. This will then be the record on which the bank will base its decision on whether to provide a loan, taking into account the down payment to Pruksa Real Estate.
Customers participating in the programme will benefit from a special promotion from the bank, including a fixed interest rate of 0.75 per cent for the first year and a loan-to-value ratio of 100 per cent.
The programme applies to the purchase of housing price up to Bt3 million per unit.
“This campaign will help our customers to get a loan during a period when the banks are restricting loan provision. It also helps the bank to screen the customers. We are trying to negotiate with other banks for a similar campaign to help our customers get a loan,” said Pruksa Real Estate’s chief operating officer, Lersuk Chuladesa.
LPN Development managing director Opas Sripayak said the company’s customers faced a rejection rate of up to 10 per cent.
Although this is well below the market average, the company has devised a way to help some of its turned-down customers meet with success at a different bank.
It does this by helping them to build up a financial history by opening a bank deposit account, and then making regularly monthly deposits. This gives them a much better chance of getting a housing loan, he said.
“Our customers have a lower rejection rate because we prepare them before they apply for a mortgage, from the moment they start the process of buying a home at one of our projects. This helps them get a loan, and also to be performing customers for the banks,” he said.
LPN also has a pre-approval programme to check its customers’ financial health before signing a purchase contract. This also helps its customers know what they have to do prior to the transfer process, he added.
Higher down payments
Land & Houses president Naporn Sunthornchitcharoen said the company’s customers had a lower-than-average rejection rate because it insisted on higher down payments than the market average.
It asks for down payments of between 20 and 25 per cent for condominiums, and 5 to 10 per cent for detached housing and town-houses.
This is a plus factor for customers when approaching the banks for a loan, he said.
Meanwhile, Sansiri president Srettha Thavisin said that before the company expanded its investment to develop condominiums priced up to Bt2 million, it told the banks that the locations would be in largely white-collar areas, where mortgage applicants could provide monthly salary statements.
“Our rejection rate is still only 10 per cent. Our customers still transfer units in line with that target,” he said.
