
Banks keeps close watch on SMEs


Banks are closely monitoring the use of credit lines by small and medium-sized enterprises after finding that some companies have being using loans for purposes beyond those approved.
Sirichai Sombutsiri, senior executive vice president of Siam Commercial Bank, said competition had allowed lenders to increase credit lines to SMEs, which was attracting more enterprises to borrow from more than one bank.
However, this means that the bank has had to increasing its monitoring of the behaviour of SME customers to ensure that the loans are used purely for stated business purposes.
Some enterprises use the money for other proposes such as purchasing vehicles, he said, adding that while the situation was not serious yet, SCB wanted its clients to use the credit for the business purposes proposed.
The bank also carefully checks a potential SME borrower’s situation |with the credit bureau to minimise the risk of a non-performing loan (NPL) developing.
Even though SCB’s NPLs are currently below 1 per cent of outstanding lending, the SME sector in particular will face pressure next year when the increase in the minimum daily wage comes into effect nationwide on January 1, as the move will affect their competitiveness, Sirichai said.
The bank next year will focus more |on medium-sized businesses with |annual sales of Bt200 million, as this segment has room to grow and a lower NPL ratio, he said.
SCB plans to increase the proportion of lending to lower medium-sized businesses to 12 per cent next year, from 7-8 per cent at present.
Patchara Samalapa, executive vice president of Kasikornbank, said it would limit credit to SME customers to three times a company’s collateral value, because the bank wants clients to use loans solely for business purposes.
The approval rate for SME loan applications at KBank is 70 per cent, he said. The bank acknowledges that new customers pose a higher risk of non-repayment than existing clients. Current customers are therefore preferred for SME lending, unless existing customers refer new clients to the bank.
“New customers that achieve the sales targets they informed the bank will be granted loan extension,” he added.
KBank will, however, build a relationship with start-up enterprises and help them to access credit even if they have no collateral to offer.
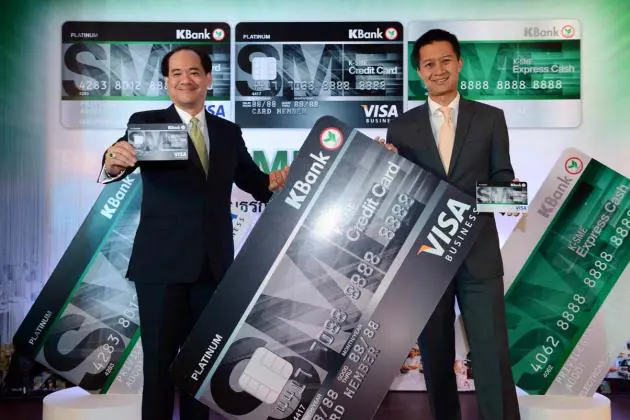
Patchara said it would do this by offering the new K-SME Debit Card, K-SME Credit Card and K-SME Express Cash Card to start-ups with attractive conditions, such as lower interest rates for the credit card, a 55-day interest-free period, against the normal 45 days, and cash-back when spending at petrol stations.
The bank targets 275,000 of the three types of SME card being issued in the first year.
Pakorn Partanapat, a KBank executive vice president, said monthly credit-card spending by SMEs was Bt30,000-Bt40,000, against an average of Bt17,000 for individual customers. Debit-card spending by SMEs averages Bt12,000, double that of the bank’s individual customers.
There are currently more than 1.43 million start-up SMEs around the country, or 54 per cent of the total number of firms of this size. They require low-cost cash reserves, cost reduction and high liquidity in the initial business stage, he said.
EXECUTIVE VICE PRESIDENTS Pakorn Partanapat, left, and Patchara Samalapa introduce |K-SME Credit Card, K-SME Debit Card and K-SME Express Cash, specially designed for access to funding, cost reduction and higher liquidity among new small and medium-sized companies.
