
BOT cool to Japan's monetary easing


Play
No adverse side effects seen on exports, weak yen a plus for imports
The Bank of Thailand, while conceding that the Bank of Japan’s monetary easing was unprecedented, does not foresee any problem as a result of that move as the two countries are not export competitors, while the weakening yen could facilitate import of cheaper capital goods for manufacturing.
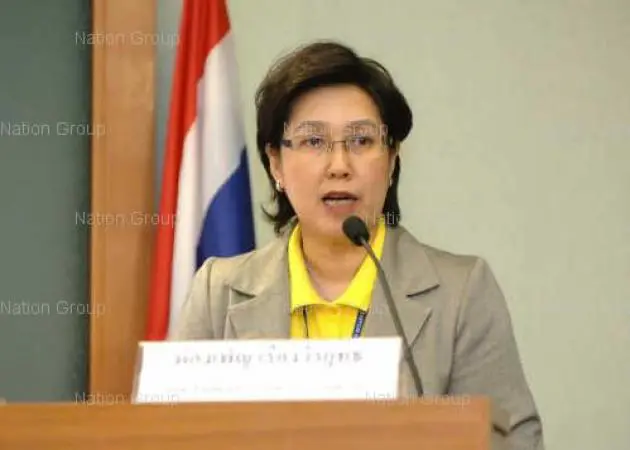
Pongpen Ruengvirayudh, the BOT’s deputy governor for monetary stability, said the BOJ’s approximately Bt40-trillion quantitative easing (QE) and doubling of the monetary base within two years were unprecedented, and the yen depreciated instantly in response to the move.
The depreciating yen could benefit the Thai economy, especially at a time when Thailand has been improving its production capacity, facilitating cheaper imports of machinery or capital goods from Japan, she said, adding that Japan was not Thailand’s competitor for exports.
Most of the Thai exports are of food products or staple goods. If the Japanese economy improves, leading to increased consumer confidence, Thailand could gain from a boost in exports to Japan.
“The yen has depreciated by 20 per cent, resulting in much cheaper imports, and the Thai business sector should pay attention to this,” Pongpen said.
The BOJ move was similar to the US quantitative easing, and will have side effects, she said. Investors will seek assets with higher returns elsewhere.
The unprecedented BOJ move, and easing concerns in Thailand about the domestic political scene, prompted the baht to appreciate slightly yesterday.
“There is no irregularity about hot money now. There has been capital inflow and outflow. We should use this time for our benefit, given the appreciating baht, low interest rates and adequate liquidity for credit extension,” Pongpen said.
In response to Thai operators’ request to the BOT to prevent the baht’s appreciation, Pongpen said the currency had been more stable and some regional peers had begun appreciating.
“Since the beginning of this year, the baht has appreciated 4.5 per cent. In the next five years, there is a chance for the baht to appreciate beyond 29 to the US dollar, and if we [the public and private sectors] collaborate for the country, the opportunity to see the baht appreciate beyond 29 per dollar could be extended,” she said.
Previous measures for the baht included allowing it to move in line with the market mechanism, support for Thai businesses to make overseas investment, market intervention and capital-control measures.
Foreign investors have continued to invest in Thai bonds and the tense situation in the Korean Peninsula does not affect the local bond market at all, according to the Thai Bond Market Association.
ThaiBMA’s head of research and market development, Suchart Thanathitiphan, said the excess liquidity, coupled with the US QE measure and low interest rate, had driven foreign money into the Asian bond markets, even without the BOJ’s launch of quantitative easing.
He added that he had yet to see significant short-term impact of the BOJ’s QE measure on the Thai bond market. But in the long term such a measure could boost inflow to the Thai market, he added.
He said the strong fundamentals of the Thai economy had attracted huge foreign investment in long-term bonds, especially those with three-to-five-year and five-to-10-year terms. He added that these were real investments, not speculative. As of March, the foreign holdings of Thai bonds were a net Bt849 billion, of which 63 per cent were in long-term bonds.
Suchart said that while the news about the tensions in the Korean Peninsula might pressure the Stock Exchange of Thailand, the bond market was less sensitive to such news and was not affected in the least.
