
Low income, access to funding key to tackle household debt: BOT chief


Play
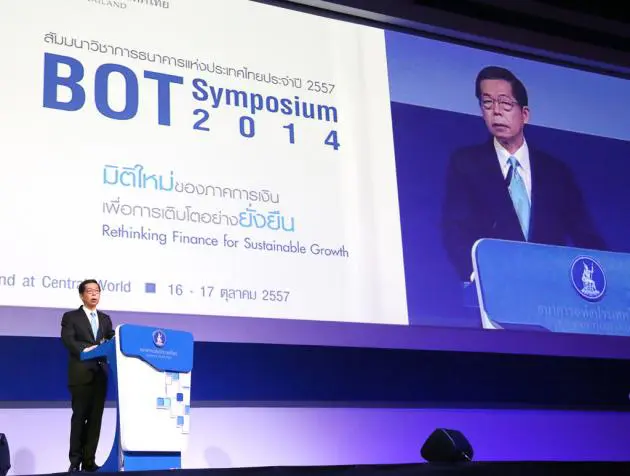
Underground loans and high household debt cannot be tackled by debt-easing measures alone, as they do not address the root problems of low income and little access to financial sources, Prasarn Trairatvorakul, governor of the Bank of Thailand, said yester
Measures such as lower interest rates and micro finance can enhance a borrower’s ability to pay off liabilities temporarily.
However, dealing with the core problems require job creation, fairer wealth distribution and knowledge on how to save more to better manage financial obligations, he told the “2014 BOT Symposium”.
Small and medium enterprises and low-income households face the biggest barrier as only 41 per cent out of the 2.7 million SMEs and less than 40 per cent of low income households could gain access to financing last year.
Charl Kengchon, managing director of Kasikorn Research, said that there had been improvements to financial access for SMEs and low income households since the 1997 financial crisis, following changes and improvements to commercial banking regulations and technology. However, there is still a need to find a way to encourage grassroots people to use formal instead of informal loans.
Banks will also need to improve their services and loan conditions to better suit this type of customer.
Interest rates do not pose an obstacle to financial access. The lack of information on customers and the high cost and lack of ability to seek and provide micro loans are more of a stumbling block, he added.
Wrongly encouraged
Prasarn said that in terms of government involvement, the previous populist policy that distorted the prices of agriculture products had wrongly encouraged a huge number of people – about 700,000 last year – to join the agriculture sector. However, now that prices of the world’s crops have dropped, it has caused a host of financial problems for all those people.
The current government stimulus measure, which aims to provide a direct cash subsidy to farmers, is suitable for the short-term but “you cannot keep on taking painkillers for the rest of your life”.
The current level of household debt at 83 per cent of gross domestic product (GDP) is not worrisome and the expansion of household debt began to slow down in the middle of last year.
However, the economic slowdown at the beginning of this year has made the problem appear to have worsened when in reality it is actually slowing down, he said.
Charl predicts that household debt would increase to about 86-87 per cent next year, assuming GDP growth of 4.8 per cent.
That level is not scary, as it has not crossed the 100-per-cent danger zone and is still manageable compared to countries such as Malaysia, 86 per cent, and South Korea, 90 per cent.
