
SCG hunts for M&As in region
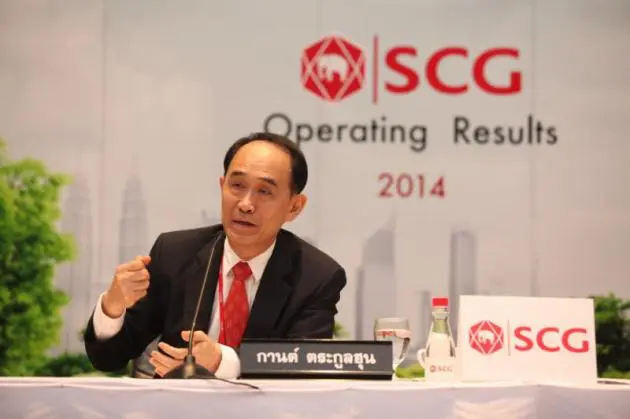


Siam Cement Group is on the prowl for mergers and acquisitions, mainly in other Asean countries, with a war chest beefed up to more than Bt10 billion this year.
SCG sees its total investment budget exceeding Bt50 billion this year, compared with Bt45.2 billion in 2014. Of total, some Bt10 billion is reserved for M&As.
Kan Trakulhoon, chief executive officer of the industrial conglomerate, said yesterday that the heftier capital expenditure budget would mainly support its existing projects, including four cement plants in Asean.
Two of them – one in Cambodia and the other in Indonesia – would be completed this year. The SCG chief voiced optimism for the group’s outlook this year, citing his more bullish forecast for the Thai economy and his expectation for Asean to witness its "golden year".
However, the movements of the baht, which has gained over other Asean currencies versus the US dollar, has hurt SCG’s profits from its investments in other Asean countries as well as its export income.
The group’s sales advanced 12 per cent to Bt487.5 billion last year, but net profit retreated 8 per cent to Bt33.6 billion.
The group’s exports surged 26 per cent to Bt140 billion in 2014, diluting domestic sales to 61 per cent of total sales from 65 per cent in 2013.
SCG’s Asean sales last year, including its exports from Thailand and sales from businesses located in the region, shot up 18 per cent to top the Bt100 billion mark for the first time.
Kan, who made a correct prediction that gross domestic product would be flat last year, is still confident the economy will pick up by 4 per cent this year, even though the consensus of research houses is around 3.5 per cent.
Domestic cement demand, thanks to government’s infrastructure projects, is expected to improve by 6 per cent this year, with volume soaring to a historical high.
SCG, where half of sales is derived from chemicals, expects to gain from the drop in oil prices, which have helped lower its financial and other costs and widened the margin between naphtha costs and its prices for polyolefin products to about US$700 a tonne.
However, the crash in oil prices has led to an inventory loss for the firm.
SCG’s profits are likely to be good this year, although revenues might grow by only 2-3 per cent because of the decline in chemical prices in line with oil prices.
The group’s 2014 net profit included a gain from the sale of shares in Toto’s sanitaryware and fittings businesses, lower earnings from the polyvinyl -hloride business of Bt1.7 billion and a Bt2.96-billion inventory loss from the chemicals business that was booked in the fourth quarter as the price of Brent crude plunged from over $100 a barrel to below $50 at present.
