
Efficiency, transparency main goals of SFI oversight switch


STATE-OWNED specialised financial institutions (SFIs) will not be fully immune to politicians’ manipulations even after their oversight is completely transferred from the Finance Ministry to the Bank of Thailand, the central bank has warned.
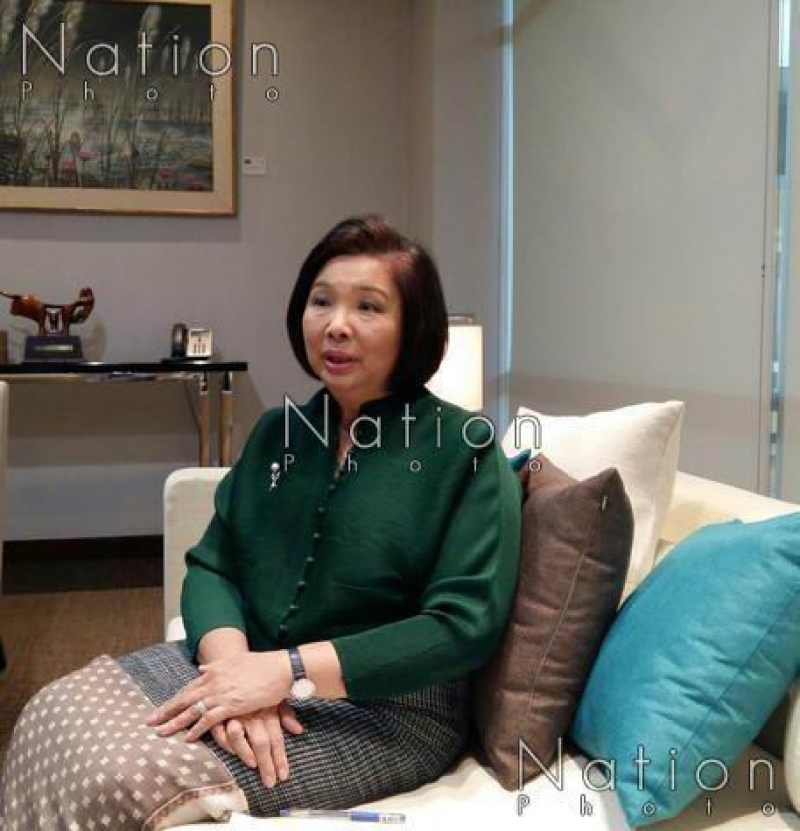
Asked about the mechanism to put an end to political manipulation completely, Tongurai Limpiti, deputy BOT governor for financial institution stability, emphasised that all would depend on the governance of the board of directors of the SFIs.
“They must raise their voice against an inappropriate order,” she said during a recent interview. “On our part, we will reserve the power to force them to disclose crucial information regarding such orders. For example, if the Cabinet approves a Bt10-billion project but the bank in question is allocated only Bt4 billion, it must be announced somewhere that the government’s funding for the remaining Bt6 billion is pending.”
The Cabinet in December 2014 approved the transfer of the oversight of SFIs’ to the central bank. Work to that end has been ongoing since then and will be completed once the Finance Ministry endorses all 24 relevant regulations, which mostly deal with loan classifications.
Lack of transparency in the operations of state-owned banks was the main reason behind the oversight switch, as eight SFIs have been seen as major political tools to vet public support of incumbent governments or boost short-term economic growth. But because of their size, a collapse could have a ripple effect on the country’s financial stability.
Chiefly, state policies have been carried out by three major SFIs: the Bank for Agriculture and Agricultural Cooperatives (BAAC), Government Savings Bank (GSB) and Government Housing Bank (GH Bank).
Deputy Prime Minister Somkid Jatusripitak in April mentioned a plan to have GSB relax lending rules for low-income earners. Lately, GH Bank was assigned to facilitate house re-mortgages.
During the Yingluck Shinawatra administration, the BAAC was under the radar as an integral part of the rice-pledging subsidy programme that cost about Bt400 billion a year. That amount comprised half of the bank’s outstanding loans in 2013. The BAAC has been a tool to assist some 20 million farmers. Other SFIs are: the Islamic Bank of Thailand, Export-Import Bank of Thailand, Small and Medium Enterprise Development Bank of Thailand, Thai Credit Guarantee Corporation, and Secondary Mortgage Corporation.
Once the changes are made, the SFIs will have to honour the same set of rules and regulations imposed on commercial banks, but to a slightly less rigid degree. Basel II capital rules will be imposed.
Loan classification will be tailored to fit the missions of each SFI. BAAC, for instance, is in no position to classify loans and set aside loss provisions every three months, because of different crop cycles.
The core banking system is to be improved, with GSB taking the lead in procurements. All will operate according to their mandates, as loan growth will be no longer part of their key performance index. However, they all must be profitable and self-supporting. SFIs will no longer be required to maintain liquid assets at 6 per cent of deposits, but must avoid letting liquidity get too low.
Major changes are expected to be seen in the boards of directors. All independent directors as well as chief executive officers and three lower management levels must be subject to the same criteria that the BOT imposes on commercial banks.
For good governance, subcommittees must be set up according to the BOT’s requirements. Theoretically, the BOT as the regulator should no longer be represented on the banks’ boards of directors, Tongurai said.
Under the pending amendment to the Financial Institution Business Act BE 2551, the central bank will have full control to investigate irregularities, and lack of action within a specified time frame could lead to closure of the institution in question. “Our main goal is to allow them to carry out their missions in a sustainable, efficient and transparent manner,” Tongurai said.
Looking ahead, she said emphasis of supervision would be placed on commercial banks’ operational risks – credit and market risks. But when it comes to these specialised financial institutions, key supervision challenges lie with personnel, information-technology systems, risk management and governance.
