
Ekniti sets Thailand’s top-20 competitiveness goal for 2030
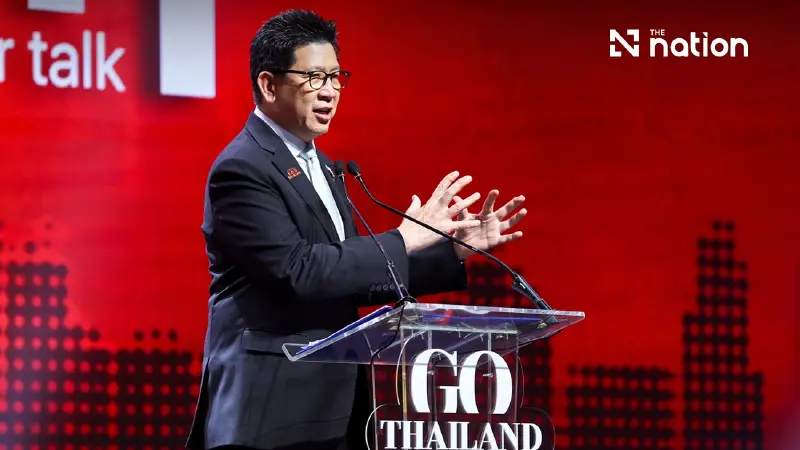


Thailand’s investment strategy aims to lift public and private investment from 23% to 30% of gross domestic product by 2030.
- Thailand's Finance Minister Ekniti Nitithanprapas has set a goal for the country to rank in the world's top 20 for competitiveness by 2030, up from its current 26th position.
- The strategy is based on investment-led growth, aiming to increase combined public and private investment from 23% to 30% of GDP and raise sustainable economic growth to an average of 3% annually.
- A "Team Thailand" approach will focus on seven key industry groups, including smart electronics, future mobility, and high-value tourism, to act as new growth engines.
- Government support for this goal includes faster investment approvals, tax measures to encourage local production, and workforce development programs like Skill Bridge to upskill Thai workers.
Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas outlined an investment-led growth strategy for Thailand on 11 November 2026, aiming to lift the country into the world’s top 20 for competitiveness by 2030.
Speaking at the “GO THAILAND 2027: NEW GROWTH ENGINES” dinner talk organised by Thansettakij, Ekniti called for investment to create lasting economic capacity, rather than relying on consumption stimulus whose effects quickly fade.
Ekniti described the transition as Thailand’s “Second Take-off” or “Next Take-off”, arguing that the country needed new growth engines after decades of dependence on those established during its industrial transformation in 1980.
Ekniti outlines three economic targets for 2030
Ekniti set out three goals for the government and private sector to work towards by 2030:
- Raise Thailand’s sustainable potential economic growth to an annual average of 3%.
- Increase combined public and private investment from 23% to 30% of gross domestic product.
- Improve Thailand’s global competitiveness ranking from 26th into the top 20.
Ekniti emphasised that attracting international capital was only part of the task. The government wanted that investment to build the skills of Thai workers and strengthen the capabilities of Thai businesses.

Seven industry teams to identify three priorities each
Ekniti called on each of seven industry groups to identify three “game changers” and strengthen connections with other sectors, so that their efforts would reinforce one another.
Under the “Team Thailand” approach, Ekniti compared the prime minister to a team manager, deputy prime ministers to coaches and private businesses to players. Industry would act as the attacking line, supported by government policy and financial stability.
The seven industry groups cover:
- Smart electronics.
- Smart automotive manufacturing and future mobility.
- Modern agriculture.
- High-value tourism.
- Wellness and medical services, with links to future foods and Thai herbal products.
- Modern retail.
- The creative economy.
Digital investment and clean energy were also among the priorities Ekniti highlighted in the wider growth strategy.

Ekniti credits faster approvals for investment growth
Ekniti attributed stronger investment inflows to efforts to remove obstacles through the Board of Investment’s Fast Pass programme. Bangkok Biznews reported that he cited a 28% increase in net foreign direct investment in the third quarter, with growth of 27–28% for three consecutive quarters.
Ekniti highlighted investment in digital businesses, smart electronics and clean energy as important sources of momentum.
Against a backdrop of increasing divisions in the global economy, Ekniti said Thailand had used World Bank and International Monetary Fund meetings to promote an approach centred on “Building Resilience”.
Ekniti presented Thailand as a “safe haven” for investment and a “strategic bridge” between conflicting interests, positioning the country to attract capital from across the world.
Tax measures and skills training support industry plans
Ekniti described tax policy and workforce development as the midfield supporting Thailand’s industry teams. The measures he outlined included restructuring excise duties on imported vehicles not manufactured in Thailand to encourage companies to relocate production to the country.
Ekniti also cited customs duties of up to 30% on imported goods purchased online as a measure to protect Thai small and medium-sized enterprises.
The Skill Bridge programme would connect new investment with workforce development, helping workers upgrade existing skills or retrain for different roles, Ekniti explained.
Financial and fiscal discipline would form the team’s defensive line, with the Finance Ministry and Bank of Thailand working together to maintain stability, according to Ekniti. He linked that stability to Thailand’s 10-year borrowing costs of around 2%.
Ekniti also pointed to the stable sovereign credit outlooks assigned to Thailand by Moody’s, S&P Global Ratings and Fitch Ratings as evidence of confidence in the country’s economic direction.
Ekniti concluded by drawing on guidance from the late King Bhumibol Adulyadej, saying that lasting success requires time, experience, accumulated effort and continuous action to deliver enduring benefits for the Thai people and economy.
