
The US and China at odds over 'world currency'


Play
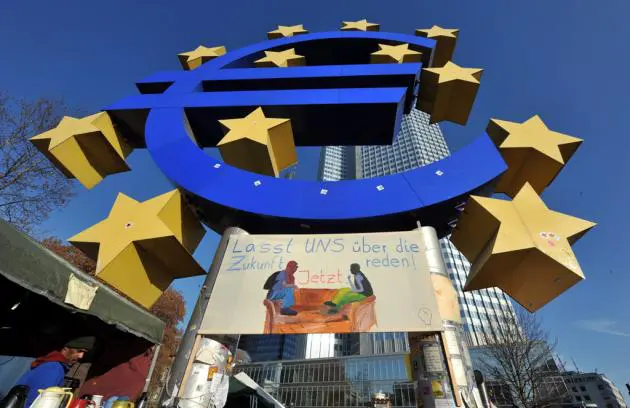
Moody's Investors Service, the rating agency, has warned about the growing risk of sovereign defaults in the euro area.
This probability is no longer negligible. In the event of defaults, the euro framework will come under pressure followed by the likelihood of one or more member states leaving the euro.
Belgian bonds have been downgraded. Portuguese and Hungarian bonds have become “junk”. Greece’s one-year bond yield has gone up more than 300 per cent. Spain is reportedly seeking a bailout from the International Monetary Fund. Italy is struggling with a debt load of US$2.1 trillion, equivalent to 120 per cent of its gross domestic product. Investors are demanding a yield of more than 7 per cent for the Italian two-year bond, up from 4.63 per cent last month. There is also a possibility that Austria and France might lose their triple-A rating status.
There has been talk that the IMF might have to come to the salvation of Italy, which would need a staggering rescue package of about $800 billion. The problem is that the IMF can’t print its own money. To help Italy, it would have to raise its capital. But most of the IMF’s major shareholders are in bad financial shape. Only China and Germany are in better financial shape. But China is not likely to raise massive capital for the IMF during this time of growing geopolitical tension. Germany won’t agree to the European Central Bank’s temptation to print money to buy up the collapsing euro bonds.
Hell will break loose if one country were to leave the euro zone. The Economist (November 26) gave a good summary as follows:
“The prospect that one country might break its ties to the euro, voluntarily or not, would cause widespread bank runs in other weak economies. Depositors would rush to get their savings out of the country to pre-empt a forced conversion to a new, weaker currency. Governments would have to impose limits on bank withdrawals or close banks temporarily. Capital controls and even travel restrictions would be needed to stanch the bleeding of money from the economy. Such restrictions would slow the circulation of money around the economy, deepening the recession.”
This week saw six central banks, led by the US Federal Reserve, launch a concerted effort to make it cheaper for banks to borrow dollars in emergencies in order to ease Europe’s sovereign debt crisis. Stocks rallied and the cost for European banks to borrow dollars dropped. But this move will only create a psychological effect without changing the gloomy outlook.
In fact, there are more incentives for the US to see a collapse of the euro so that the euro-zone countries can go back to embrace their own former currencies. The dollar is no safe haven at this juncture because of the high deficit and unsustainable public debt and obligations of the United States. If the euro were to disappear from the scene, the dollar would safeguard its status as the world’s reserve currency. But to prolong the death of the euro, Europeans could sell off dollar assets, which would prop up the euro.
Amid the wobbling euro and dollar, the Chinese yuan could emerge to become another global reserve currency. China is the richest country on earth in terms of foreign exchange reserves, holding more than $3.2 trillion. It could buy up most assets in the world. If China were to float the yuan and gain the confidence of the global financial markets, the yuan would rival the dollar as the reserve currency. China would then enjoy the privilege, similar to the US, of printing the yuan for the world.
The US’s Middle East and African strategy is partly aimed at curtailing China’s access to oil and natural resources in those regions. Recently, it has mounted a flurry of diplomatic activity in Asia in order to contain China. Ultimately the goal is to prevent the rise of the yuan as the global reserve currency. South Korea, Japan, Australia, Indonesia, the Philippines, Thailand, Singapore and Vietnam appear to have joined an emerging security arrangement to contain China. US Secretary of State Hillary Clinton paid a two-day visit to Burma this week in order to further drive a wedge between Burma and China.
While the euro is struggling to survive, we are seeing a confrontation between the US and China both militarily and financially to become the ultimate printer of the global currency.
