
Thailand Unveils ‘STI DEE’ Blueprint as Finance Ministry Becomes Prototype for National Reform
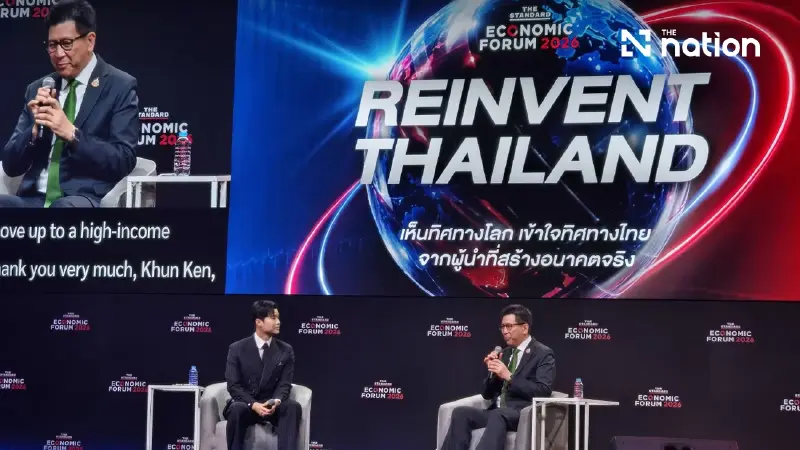


Deputy PM says the ministry will publish five years of procurement data on Monday (November 9), hold the 70% debt ceiling and use BOI incentives to lift Thai skills and wages
- Thailand's Finance Ministry will act as a prototype for national reform under a new strategy named "STI DEE", part of the government's "Reinvent Thailand" agenda.
- The "STI" component of the blueprint focuses on Stability, which includes maintaining fiscal strength, keeping the public debt ceiling at 70% of GDP, and promoting investment.
- The "DEE" component stands for Disclosure, Ease, and Efficiency, which will be implemented by publishing five years of procurement data for public scrutiny and using digital tools to simplify government services.
- The plan also involves using Board of Investment (BOI) incentives to shift focus towards actual investment, job creation, and lifting Thai skills and wages.
The Deputy PM says the ministry will publish five years of procurement data on Monday (November 9), hold the 70% debt ceiling and use BOI incentives to lift Thai skills and wages.
Thailand’s Finance Ministry will become the first test case of the government’s “Reinvent Thailand” agenda, with a sweeping overhaul built on transparency, digital services and efficiency, Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas said on Wednesday (Novermber 4).
Speaking in a panel discussion at the opening of “Economic Forum 2026: Reinvent Thailand”, hosted by The Standard, Dr Ekniti said the ministry would be a “prototype” for reform. Its strategy, named “STI DEE”, will be formally unveiled on Monday, he said, although he previewed its main elements on stage.
The first element is stability, covering fiscal strength, the energy transition and investment. The second, “DEE”, stands for disclosure, ease and efficiency.
Disclosure is the most radical. The ministry will open its procurement data from the Comptroller General’s Department, going back five years, so that the public and lawmakers can scrutinise it.
“I will open the wounds,” he said, so that problems can be seen and solved together.
He noted that last year’s budget data was released in machine-readable form, which MPs from both government and opposition have used for AI-driven analysis.
He intends to brief parliament on the approach on Thursday (November 5). “Ease” means using digital tools to make dealings with the state simpler. “Efficiency and effectiveness” means the public sector should drop what it does not need to do and leave to private firms what they can do better.

No compromise on discipline
Dr Ekniti was unequivocal that fiscal discipline remains the foundation of his policy, describing it as the team’s “back line” in a football analogy. The deficit, which was projected at 4.4% of GDP, closed the fiscal year ended September at 3.4%, a result he said had won global praise.
All three major credit rating agencies have moved their outlooks on Thailand from negative to stable. The benefits reach households and businesses, he argued.
He said the ten-year government borrowing cost in Thailand is about 2%, against close to 5% in the United States, nearly 8% in Indonesia, roughly 4% in Malaysia and 2.3% in Singapore, on the figures he quoted that morning. Public debt is about 67–68% of GDP, he said, and he wants it to fall.
He ruled out lifting the public debt ceiling, which stays at 70% of GDP, compared with global norms of 90–100%. He rejected the idea of using the 200 billion baht emergency loan decree simply to spend it.
“If it is not all used, that is fine,” he said, stressing efficiency and effectiveness.
Revenue: fairness over burden
On revenue, he said collection had exceeded targets, helped by digital systems. The government had aimed to cut the deficit below 3% within three years and was close to achieving it. He defended the cabinet’s proposed rise in excise tax on cars, particularly imported ones, as an action meant to achieve several aims at once.
It would ensure fairness for foreign investors who employ Thais and build local supply chains, he said, and raise revenue. Investors had pleaded with him, he said, as imports flooded in.
The global minimum tax, set at 15% under international rules, was already generating about tens of billions of baht in additional corporate income, he added.

He said the government had held back on some tax measures, including one affecting air travel, because high oil prices from the Middle East conflict had already pushed up fares.
Tourism and jobs, he judged, were worth more than the revenue, and the measure would wait for the right moment. He also aims to bring people outside the tax system into it so that those who pay do not resent neighbours who do not.
Investment as a tool
As chairman of the Board of Investment (BOI), Dr Ekniti said he had changed the agency’s targets. It now measures actual investment rather than applications, plus jobs created and skills developed. Since the start of the year, BOI-backed projects had generated about 120,000 jobs.
Actual investment grew about 27% in the third quarter, he said, and a recent round of projects was worth around 600,000 million baht. He tells investors to build a “skill bridge”, asking how many Thais they will hire and train.
One top-two global firm in optical data transfer is expanding in Saraburi and Ayutthaya, employing 30,000 people, with research ties to Thammasat University and Suranaree University of Technology in Nakhon Ratchasima.
Thailand, he said, is in the global spotlight after hosting the IMF–World Bank meetings, as a neutral trading nation in a fragmented world. The country must catch the “high-speed train” passing through it.
Seven private-sector-led industries will announce key performance indicators on Monday (November 9): modern agriculture, food processing, smart electronics, electric vehicles, wellness and others.
Old sectors will be upgraded rather than abandoned, he said, with tourism shifting from “sickness” to wellness.
Energy and people
The 200 billion baht loan decree, he said, targets three areas: electricity, transport fuels and skills. About 70 billion baht has been approved, including 50 billion for household solar, with subsidies and the right to sell power back, and the rest for smart meters and grid upgrades.
Around 100 billion more is planned for transport, including E20 petrol, B20 diesel and locally built pickup trucks. For people, about six million Thais aged 20–60 earn under 100,000 baht a year and will be retrained with the education and labour ministries.
By 2030, he said, Thailand should post GDP growth above 3%, lift investment from 22% to 30% of GDP, and climb from 26th to the top 20 in competitiveness within three to four years. Growth must spread beyond the wealthy, he said, addressing the K-shaped recovery. This might be Thailand’s “last chance”, he added.
