
ROH Contests GROREIT Asset Sale Resolution, Maintaining Contractual Buyback Rights for Sheraton Hotel
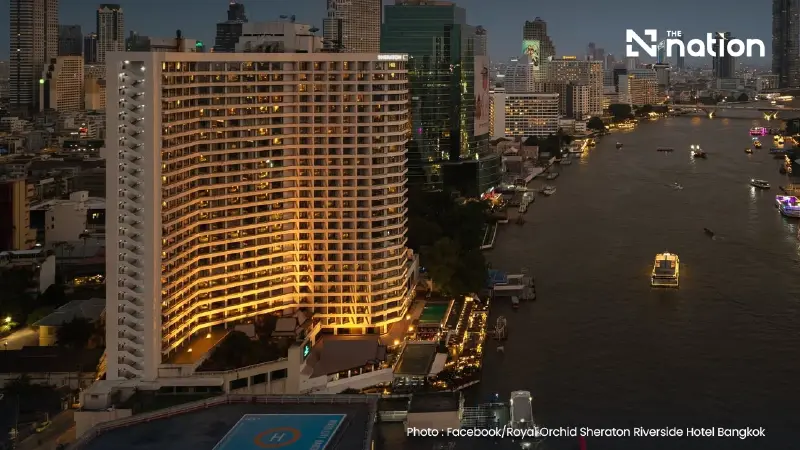


Royal Orchid Hotel challenges GROREIT’s assertion that its repurchase rights have expired, seeking legal counsel ahead of a critical unitholder vote
- Royal Orchid Hotel (ROH) is formally contesting a resolution by GROREIT to sell the Royal Orchid Sheraton Hotel, asserting that its contractual right to repurchase the asset remains legally valid.
- The dispute stems from GROREIT's position that ROH's buyback rights expired on July 14, 2026, after a missed deadline, prompting the REIT to schedule a unitholder vote to approve the property's sale.
- In response to the planned sale, ROH has declared its opposition and is consulting with legal advisors to protect its rights ahead of the vote.
- GROREIT's unitholders will consider three disposal options: a conditional sale back to ROH, a competing THB 5.3 billion offer from another company, or an open auction.
Royal Orchid Hotel challenges GROREIT’s assertion that its repurchase rights have expired, seeking legal counsel ahead of a critical unitholder vote.
Royal Orchid Hotel (Thailand) Public Company Limited (ROH) has formally declared its opposition to a resolution by the Grande Royal Orchid Hospitality Real Estate Investment Trust with Buy-Back Condition (GROREIT) to sell the iconic Royal Orchid Sheraton Hotel & Towers.
In an official filing submitted to the Stock Exchange of Thailand (SET) on Friday (September 18), Sanith Adhyanasakul, director of ROH, clarified the company's position following GROREIT's call for Unitholders' Meeting No. 1/2026 on 28th October 2026 to deliberate on the disposition of the landmark riverfront property.
Disputed Repurchase Rights
The conflict stems from a joint position taken by One Asset Management Limited (acting as the REIT Manager) and MFC Asset Management Public Company Limited (acting as Trustee).
Both entities maintain that ROH’s contractual right to repurchase the hotel project under the original purchase and sale agreement expired on 14th July 2026, when ROH failed to complete the buyback transaction valued at 4.873 billion baht.
ROH strongly refutes this interpretation, asserting that its contractual option to repurchase the prime asset remains fully intact and legally binding.
The company confirmed it is currently consulting with external legal advisors to evaluate necessary and appropriate actions to safeguard its rights and protect its commercial interests prior to the scheduled unitholder vote.
Handover Demand and Asset Disposal Options
Following the missed July deadline—established when the GROREIT trust was originally formed in 2021—One Asset Management issued formal notice instructing ROH to vacate the premises and hand over full operational control of the property within 30 days, a deadline that lapsed on 15th August 2026.
As title ownership of the land deed is already held by the trust, the REIT manager is moving forward with plans to liquidate the fund, expecting the entire handover and winding-up process to take approximately six months:
Disposal Options: Unitholders will consider three potential routes at the 28th October meeting:
- Approving a THB 4.873 billion repurchase offer from ROH (subject to specific conditions and a 14-day execution timeframe).
- Approving a competing THB 5.3 billion acquisition offer submitted by Orchid Hospitality Co., Ltd.
- Authorising an open auction process as a fallback if preceding proposals fail.
Capital Return: Following an asset sale, funds will be allocated to settle liabilities—including primary debt owed to Government Savings Bank—before distributing the remaining capital to unitholders and liquidating the trust.

Despite the legal deadlock and corporate dispute between the trust and the former owner, day-to-day operations at the 5-star hotel continue without disruption.
To ensure revenue flows directly to the trust rather than the former operator, the trustee has coordinated with Starwood (under Marriott International) to manage the property directly.
Trading performance remains robust, with the Royal Orchid Sheraton recording an average occupancy rate of 72% over the past year.
