
Ekniti outlines 3-pillar strategy to strengthen Thailand’s economy in a fragmented world
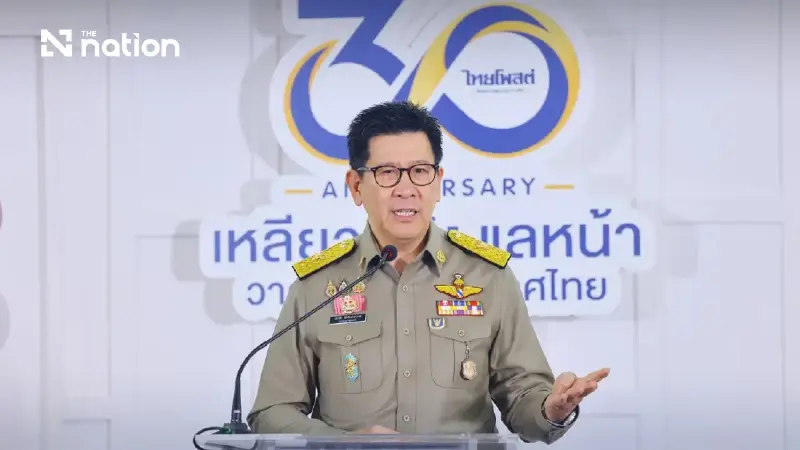


Ekniti calls for clean energy, stronger skills and closer public-private cooperation to attract investment and strengthen Thailand’s economy.
- The first pillar, "Stabilize Today," aims to ensure financial and fiscal stability through debt relief programs and liquidity support for small businesses, backed by strict fiscal discipline.
- The second pillar, "Transition Now," calls for an urgent shift to clean energy to reduce Thailand's dependence on imported oil and gas and protect the economy from global energy price shocks.
- The third pillar, "Invest for Tomorrow," focuses on strengthening long-term growth by investing in technology, modern infrastructure, and upskilling the workforce, while encouraging foreign investment that integrates with local supply chains.
Ekniti Nitithanprapas, Thailand’s deputy prime minister and finance minister, outlined a three-pillar economic strategy on October 5, 2026, to safeguard financial stability, accelerate the clean-energy transition and strengthen investment in an increasingly volatile and fragmented world.
Speaking at a forum marking Thai Post’s 30th anniversary, themed “Looking back, looking ahead and shaping Thailand’s future”, Ekniti said the “STI” strategy would help Thailand build solid foundations and create opportunities in a global economy increasingly operating without clear rules.
Fiscal discipline underpins debt relief and business support
Under “S: Stabilize Today”, Ekniti identified financial and fiscal stability as Thailand’s first line of defence while tackling longstanding economic weaknesses. These include sluggish growth linked to persistent underinvestment since the 1997 financial crisis, high household debt and limited access to credit for small and medium-sized enterprises (SMEs).
Ekniti said debt relief through the “Clear Debt Fast, Move Forward” programme, alongside liquidity support for SMEs, must be backed by strict fiscal discipline to sustain capital-market confidence. He pointed to credit-rating agencies’ revisions of Thailand’s outlook from negative to stable as evidence that the approach was working.

Ekniti calls for an immediate clean-energy transition
The second pillar, “T: Transition Now”, requires urgent changes to Thailand’s economic and energy structures, Ekniti said. The country’s oil and natural gas imports are worth almost 10% of gross domestic product, leaving the economy exposed to overseas energy shocks.
Ekniti linked higher oil prices to damage to global energy infrastructure caused by conflicts and wars abroad. He said the resulting pressure had contributed to a Thai current-account deficit of 600 billion baht in the second quarter.
Ekniti called for the government to accelerate the shift to clean energy and upgrade the electricity transmission network. The transition would cushion the impact of expensive oil, reduce energy imports and allow households to become electricity sellers as well as consumers, cutting expenses while generating income, he said.

Investment strategy links technology with Thai workers and suppliers
Under “I: Invest for Tomorrow”, Ekniti said Thailand must follow stabilisation and structural reform with investment in machinery, technology and modern infrastructure. Investment in people, through upskilling and reskilling, would also be essential as the population ages.
Ekniti said revised Board of Investment (BOI) rules placed greater emphasis on turning investment plans into actual projects, supported by Thailand Fast Pass and the Thailand Skill Bridge workforce development initiative.
Foreign investors must connect their supply chains with Thai SMEs and transfer technology to Thai universities, including Suranaree University of Technology and Thammasat University, Ekniti said. He highlighted artificial intelligence and semiconductors, describing Thailand as a global manufacturing base and saying the approach would create jobs and develop skills for tens of thousands of Thai workers.
Government-business cooperation targets seven economic sectors
Ekniti drew parallels with the economic shifts of 1980–1985, citing the Plaza Accord and pressure from the United States and Europe for the yen to appreciate. He described the currency’s rise as occurring overnight, prompting Japanese manufacturers to relocate production to Thailand.
Ekniti linked that relocation to the development of the Eastern Seaboard and major industrial infrastructure, which helped transform Thailand from an agricultural economy into an industrial one.
Global fragmentation was creating another opportunity for Thailand, Ekniti said, as investors looked for safe locations able to trade with all sides. Investment promotion applications reached 1.47 trillion baht in 2025, which he cited as evidence of the country’s appeal.
To capture those opportunities, Ekniti said the government had revived cooperation through the Joint Public-Private Committee, chaired by the prime minister, to advance seven priority economic sectors.
Ekniti outlined four areas of government support: promoting modern investment through the BOI; developing people and education; supporting SMEs; and improving regulations. Financial and fiscal stability would remain essential to sustaining growth, he said.
“The STI strategy and systematic cooperation between the public and private sectors will be key to helping Thailand navigate the challenges of this new global era with confidence. I believe that if we can move forward together in this way, Thailand’s future will improve,” Ekniti said.
