
Central banks chained to the printing press
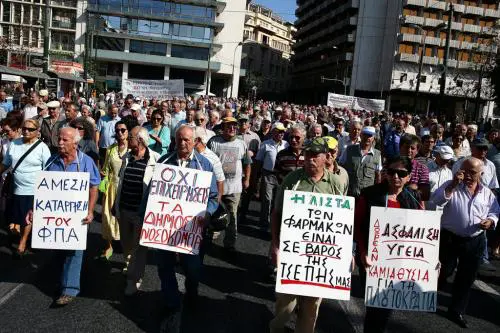


Greece is facing the inevitable - a default on its debt. Its workers are holding massive strikes against the government's austerity programme.
There is no way out for Greece, except down, down and down further.
The European policy-makers and the International Monetary Fund are revising key measures to bail out Greece, which can’t possibly meet its obligations to fulfil the original support programme.
Some of the measures have been tabled as follows:
Holders of Greek debt will have to take a 50 per cent haircut. That means Greek debt will be reduced from 340 billion euros to 170 billion euros.
Interest paid on Greece’s debt will have to be cut, probably to zero per cent.
With the interlocked lending and borrowing among the banks and governments in Europe, it will be necessary for the European Union to expand the size of the region-wide bail-out fund. In this regard, the financial stability fund will probably have to be increased from 440 billion euros to 2 trillion or 3 trillion euros. In the process, the European Central Bank (ECB) will have to go to the printing press. The ECB, of course, is finding ways to recapitalise the European banks, which will have to take a hit on debt default in a chain-like effect.
Central banks are now being hooked to the printing press. The Bank of England is pondering another round of monetary printing to stimulate growth. In its first round of money printing, the Bank of England churned out 200 billion pounds sterling to prop up the financial system.
The US Federal Reserve unofficially handed out US$16 trillion in the aftermath of the Lehman Brothers collapse to bail out the big banks, investment banks and also foreign central banks during the seize-up of liquidity.
Officially, the Fed has completed its second round of quantitative easing to the tune of $600 billion. Now the Fed is trying to influence the long-term interest rates by planning to use its proceeds from the shorter-term US Treasuries to buy up the long-term US Treasuries. The financial system can’t ever have enough liquidity.
And now the ECB is under pressure to save the too-big-to-fail banks. A massive amount of capital will be needed to rescue these big European banks, which will have to write down their capital from the debt default. The ECB, too, is about to plunge into this course of money printing to save the banks.
Since Greece has adopted the euro, it has transferred its sovereignty to the ECB. If it had opted to stay outside the eurozone, it would have been able to print its own money now to avoid outright default.
Nonetheless, money printing, in the strict sense, is a kind of default because it devalues the currency and lowers people’s purchasing power. In other words, it brings about monetary inflation.
The consequences for the other global currencies will be awful if the money printing continues on this large scale. For holders of the major currencies, such as China, India and other oil-rich countries, they will be asking themselves: Why should they need to hold on to the depreciating currencies that are going to be worthless in value because of the money printing.
What will happen if the newly emerging economies such as Russia, Brazil, China and India decide to unload their assets held in the major currencies? Don’t ever think that this could not happen. For it will be better for these countries to get rid of assets with depreciating value now rather than hold on to them until they become worthless later.
In the meantime, we can see the double standard of the IMF. During the Asian financial crisis of 1997, Thailand, Indonesia and South Korea were under pressure not to default or adopt a debt moratorium. These countries had to pay off their debt to all foreign creditors and bond-holders.
Saving the foreign creditors is the job of the IMF. Thailand paid its creditors in full by devaluing its currency and selling off its assets. Other austerity measures included high interest rates, budget tightening and financial sector reform.
But now Greece may be allowed to default.
International rules are designed to impose on the developing nations. When it comes to the developed nations, they can improvise to adjust the rules any time to suit their interest and convenience.
