
Disruptive fintechs should be ‘encouraged’


Play
Kasikornbank gears up for leading role in new era
While digital technology is disrupting the traditional way of business in all industry sectors – including the financial and banking industry where “fintech” has an increasing and similar role – the government of Thailand is launching a National e-Payment scheme to move forward an electronic payment system in the Kingdom.
One of Thailand’s leading banks, Kasikornbank, is preparing itself for competition in this world of digital disruption in order to become also one of the most innovative banks in Southeast Asia.
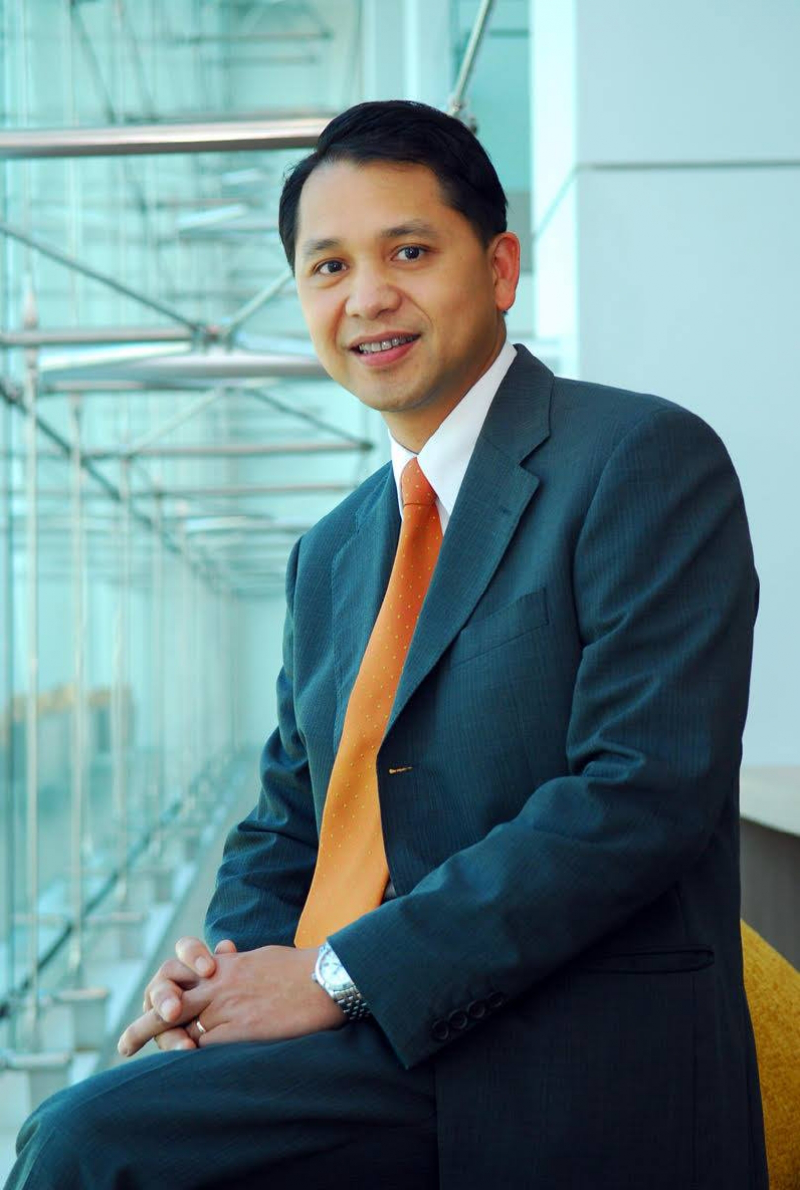
The Nation’s Asina Pornwasin interviewed Teeranun Srihong, president of Kasikornbank and chairman of Kasikorn Business-Technology Group, about his bank’s direction in these times of digital disruption.
Do you have opinion about this trend to fintech? Is it an opportunity or threat to KASIKORNBANK?
A number of banks may view fintech as a direct threat to banks with its innovation, better knowledge of millennial consumerism, and lean startup approach. We have a totally opposite view. We believe the innovative solutions and working approach of these technology startups should be encouraged, embraced and even accelerated. We should try to get them to help us simplify and revolutionise the way we provide banking services to our stakeholders. It is very clear that banks and fintech can, and should, look at ways to learn from each other for the better good of the industry, our customers and the society as a whole.
At KBank, we have been actively searching for ways to build innovative solutions in our digital transformation journey, whether it’s by improving customer interactions, reducing waste through workflow efficiency, and offering unique products and services. However, along the way, we’ve always wished we could have delivered those solutions at a faster pace and with lower costs. KBank, therefore, recognises the potential of engaging with tech startup ecosystems, locally and abroad, and fostering communication and collaboration with them. Let me be clear, though, we do not see these innovative firms as merely supporters of our solutions. Rather, we view them as a crucial component in our innovation efforts. We do plan to integrate their technology and offerings directly into our banking platform with the end goal of creating practical solutions to support our respective customers. Moreover, we hope to help them to increase their chances of success and continue to innovate in a sustainable manner.
Furthermore, we believe that KBank, along with our strategic, innovative technology partners, can lead innovation in the Thai banking sector by focusing on the following three pillars:
lUtilization of Big Data in real time to enhance speed and efficiency and to increase the pace of new product innovation as well as service offerings through data analytics
lMastering customer relationship and experience by creating brand loyalty and personalised services
lEmbracing the digital innovation, internally and externally, by encouraging innovative culture within KBank and be part of startup ecosystems.
What is KASIKORNBANK’s business plan related to the fintech, both in short term and
long-term?
KBank is committed to be one of the most innovative banks in Southeast Asia, and we intend to continue raising the bar with that reputation. We are reaching out, as well as attracting tech startups to communicate and potentially collaborate with us. KBank can offer access to funding and along with other support services; such as providing further market reach through our established SME/merchant and mobile banking base, sharing our experience to help them build practical solutions, allocating our IT infrastructure to scale their innovation, and integrating our security and regulatory compliance to their platform – as well as offering quick turnaround of PoC and extending our APIs for innovators.
KBank also understands the importance of digital banking and recognises technological trends in mobile applications, big data analytics, security, Blockchain, and the socialisation of finance. Thus, we have pushed forward to be at the forefront of innovation in the AEC+3 region by setting up a new, wholly-owned subsidiary, Kasikorn Business-Technology Group (KBTG), which was launched earlier in January. KBTG is led and governed by our top management team. It is tasked with experimenting, prototyping, and developing radical innovations by utilising customer-centric and multi-disciplined approach. Upward visioning and open ideation [the formation of ideas and concepts] process will be encouraged. It will be the platform we use to develop innovative digital products in collaboration with tech startups, tech giants and our academic partners. Furthermore, while KBTG is organised independently from the bank, our innovation efforts will be tightly integrated with the bank to ensure synergy and ability to leverage strengths of each other for mutual successes of the bank and our partners.
Which are the areas of fintech that KASIKORNBANK sees as opportunities?
Generally we want to see innovative products/services, or an improvement that can be applied in the way we’re doing banking businesses. It doesn’t have to be “fintech”, but rather any “tech startups” that would offer value creation and relevancy to our business operations. We’re looking for those alluring, innovative ideas that will excite us. Then we ask ourselves, can this “sexy” idea be applied in our markets? Who would be our customers? How will they benefit? And how is it relevant to our businesses? An innovative product can be a great idea, but if it’s not applicable to our ecosystem, or doesn’t have a practicality aspect, it’s not as appealing. Finally, we want to see that the company is backed by an experienced and talented management/advisory team. If a startup can adequately answer these issues, they have our attention.
There are five areas of focus that have caught our interest:
lCustomer engagement & experience – think loyalty programme, location-based offerings, gamification [to capture consumers’ attention and keep it], PFM, digital marketing, and business marketplaces.
lBig data & analytics – think natural language processing, text & voice analytics, credit risk valuation, and business intelligence tools
lFinancial technology – think Blockchain, payment/remittance services, digital wallet, mobile banking, portfolio management, P2P/crowdfunding platforms, and IoTs
lEnterprise IT, infrastructure & security – think Blockchain, biometric authentication, API-based banking, workflow automation/digitisation, and worker enablement
lAI/machine learning – think robo-adviser, virtual experience, predictive analytics, and machine automation
We may engage them as a strategic partner, an investor, a mentor, or even a customer. That will depend on each innovation/firm and how they are aligned with our strategic imperatives.
How does KASIKORNBANK prepare for the government’s National e-Payment policy?
KBank is determined to maintain our digital banking leadership in line with technology advancement amid the changing consumer behaviour and government policies promoting a digital economy, including the National e-Payment Master Plan and the Bank of Thailand’s Payment Systems Roadmap. KBank has thus devised operational guidelines and upgraded our IT system to accommodate the changes, as follows:
lAny ID Money Transfer: KBank is developing our IT system to accommodate the Any ID Money Transfer wherein registered ID, which can be national ID or mobile phone number, is used as a reference. The programme is intended to promote e-payment and reduce the use of cash and to accommodate the distribution of government welfare funding to the general public in the future. In cooperation with other commercial banks via the Thai Bankers’ Association, Any ID Money Transfer processes and conditions for registration are being established with the highest system security. Currently, systems to link the central database and payment via KBank channels as well as for electronic bill payment & presentment (EBPP) are being developed.
lCard expansion: To reinforce our number-one position in the debit card market, we have expanded our debit cardholder base with the issuance of debit cards under the Local Card Scheme. In addition, the expansion of EDC service is in the pipeline to promote e-payment, e.g., via debit cards and/or mobile phones.
le-Tax: Guidelines have been established for the development of comprehensive payment systems, eg e-Invoicing, e-Supply Chain, e-Logistics, to assist our customers in business management. Along with this, we consistently upgrade our electronic channels to better serve our customers, while also equipping them with beneficial knowledge on the benefits, convenience and safety of electronic transactions to encourage their migration to e-payment use.
le-Payment Government: KBank has set out a plan to implement a system for customer registration with national ID that will be linked to the central database. The new payment plan is expected to accommodate direct funds transfer for welfare disbursement, for improved access to citizens in genuine need.
lMarket education and activation programme: To remain at the forefront as a digital banking provider, we will be enhancing our capacities for digital banking channels to meet the diverse needs of customers. Knowledge about e-transaction safety will be disseminated to the public, to promote greater use of electronic payment.
What is the direction of KASIKORNBANK’s innovative financial businesses and services?
The emergence of fintech can generally be attributed to rapid changes in technology, millennials’ consumerism, and regulations.
In Thailand, the importance of big data analytics, mobile accessibility, location – and preference-based tracking, and new distribution channels have given rise to a sort of entropy of digital banking disruption that allow fintech to differentiate from incumbent banks. Though Thailand is still a cash-dominated society and lags behind – compared to the Western markets – we’re expecting to see these new entrants expanding, but not taking, the pie in financial services industry that were unfortunately underserved by banks.
On the consumer front, millennials are demanding more transparency, improved UX/UI, automation, always-on access, and lower-cost transactions. They are driving the change in consumer behaviour that forces banks to meet the new minimum standards for financial services from here onwards.
Regulations have also restricted banks practising risky investments/lending, set high capital requirements, and made us more accountable for consumer protection. Moreover, the landscape will become more favourable for fintech to enter the market as our government is pushing to create a tech startup ecosystem and to reshape competition in traditional bank activities. We will also see regulatory changes aimed to gradually move work processes, verification, authentication, filings, e-payment system, etc. on to cloud-based platforms – allowing innovation in financial services to thrive.
The three factors mentioned above prompted KBank to adjust our digital strategies. We believe there are four major financial sectors that will be impacted the most by fintech in Thailand – payment, personal finance, retail investment, and lending. Other sectors that we’ll be sure to keep close watch on are mortgages, insurance, and remittances. We’re learning and adapting to better our services as we identify customer pain points, new technological architecture, and process efficiency. Each sector has its own unique characteristics, and how we leverage will need to be adjusted accordingly.
