
Hall and Woodford win Nobel economics prize for stabilisation models
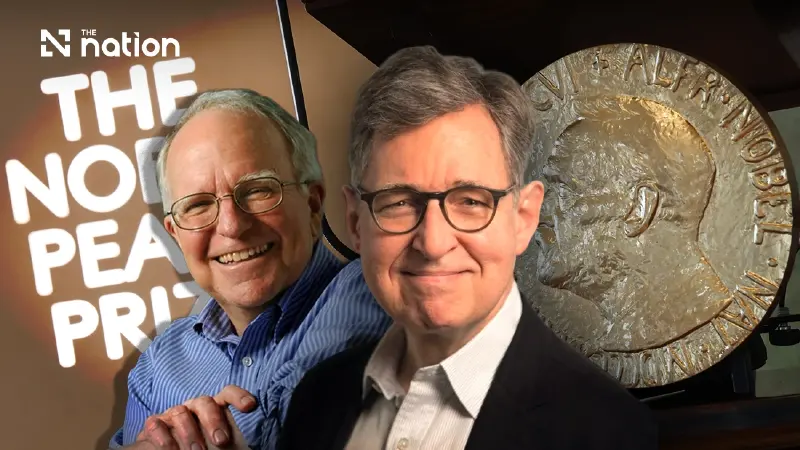


Robert E. Hall and Michael Woodford’s models account for household and business decisions, showing how timely fiscal and monetary measures can ease economic swings.
- Robert E. Hall and Michael Woodford won the 2026 Nobel economics prize for creating new macroeconomic models that improve economic stabilisation.
- Their models are built on microeconomic foundations, focusing on how the decisions and future expectations of individual households and businesses affect the overall economy.
- The work shows how governments and central banks can moderate economic booms and downturns by communicating policy to influence public expectations.
- These models now form the theoretical basis for economic policy and analysis used by central banks and governments worldwide.
Robert E. Hall and Michael Woodford have won the 2026 Nobel economics prize for developing new macroeconomic models that improve the ability to implement economic stabilisation policy effectively.
The models show how fiscal and monetary measures taken at the right time can moderate economic booms and downturns.
Their work underpins models used by governments and central banks worldwide, focusing on the decisions of households and businesses and how their expectations about the future affect the wider economy.
Oil crisis exposes limits of Keynesian thinking
Economic activity alternates between slowdowns and expansion.
Stabilisation policy has played an important role in managing these fluctuations since John Maynard Keynes proposed his theory almost a century ago.
During recessions, this approach calls for lower interest rates and larger budget deficits to stimulate the economy.
When economic expansion becomes too strong, the opposite measures should be taken to slow it down.
During the oil crisis of the 1970s, however, Keynesian models used to determine when and how to intervene appeared to become ineffective.
The measures did not reduce unemployment and instead led to uncontrolled inflation.
The West experienced a decade of low growth, high unemployment and high inflation, leaving many believing that stabilisation policy did more harm than good and should be abandoned.
Models grounded in household and business behaviour
Hall and Woodford received the prize for demonstrating how economic models could be rebuilt to restore the effectiveness of stabilisation policy.
Their models use microeconomic foundations in place of statistical relationships between macroeconomic variables such as inflation, output and consumption.
Their approach examines how the decisions and actions of individual households and businesses combine to shape the economy.
A key feature of these models is that households and businesses consider the future when making decisions about saving or setting product prices.
Expectations therefore influence economic behaviour and are an important part of understanding the effects of policy.
Policy communication shapes expectations
By communicating their economic policy plans, governments and central banks can shape households’ and businesses’ views of the future and help steer the economy in an appropriate direction.
Since their introduction, the new models have helped considerably in responding to economic downturns.
Better prepared for economic shocks
John Hassler, chair of the Committee for the Prize in Economic Sciences, said the two laureates’ work had established a sound theoretical basis for the models used today by central banks and governments worldwide.
These models help improve preparedness for economic shocks, including energy crises and sudden changes in household consumption.
